SoFi: Bank, Investing & Crypto
- 21.64K
- 3.8
- Installs
- 5.00M
- Price
- Free
Screenshots
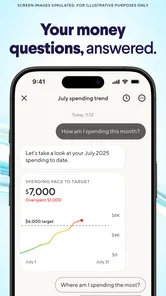
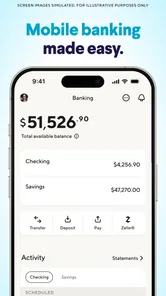
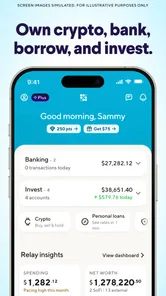
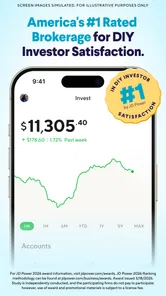
Analysis by Reviewed
When it comes to managing finances, having everything in one place is a dream for many. Enter SoFi - Banking & Investing, the all-in-one financial app that promises to revolutionize the way we handle money. If you’re like me and juggling between different banking apps and investment platforms feels like a chore, then let me walk you through my experience with SoFi.
A household money routine
I find the app most useful when one person wants a quick view of their own day-to-day banking and investing without hopping between several services. Picture checking a balance before groceries, setting money aside for a personal goal, then looking at an investment account later. Keeping those activities in one app can make the routine feel less scattered, especially for someone who already wants both banking and investing in the same place.
That convenience does not make it a shared household ledger. I would treat each person’s financial activity as their own and avoid passing around sign-in details or leaving an unlocked phone where another household member could act on an account. For couples or roommates coordinating bills, a separate shared spreadsheet or agreed household budget can still be useful; the app’s broad financial scope should not be mistaken for a dedicated family-control tool.
Seamless Banking Experience
One of the first things I noticed about SoFi - Banking & Investing is its incredibly user-friendly interface. Setting up an account was a breeze, and within minutes, I was exploring all the features it had to offer. The banking section is straightforward and intuitive. No more waiting in long lines at your local bank branch because everything you need is right at your fingertips.
The app offers a plethora of banking services, from checking and savings accounts to loans and credit cards. What’s really cool is the absence of any account fees, which is a rare find these days. Plus, the ability to earn competitive interest rates on your savings makes SoFi a strong contender in the digital banking space.
Setting boundaries before you combine money tasks
Before I rely on a single finance app, I decide which jobs it should handle and which still belong elsewhere. For example, I might use it to review my personal spending and savings while keeping a household bill calendar outside the app, where everyone who needs it can see the same due dates. That division keeps convenience from turning into confusion about who is responsible for a payment.
I would also avoid treating an investment balance as cash available for near-term expenses. A useful habit is to check the account type and purpose before moving money or making a trade: emergency savings and money intended for investing are not interchangeable just because both appear in a finance app. For someone new to investing, taking time to understand an option before acting is more valuable than having every feature close at hand.
More From Our News Desk

 Bolt: Request a Ride
Bolt and the Shift from One-Tap Rides to More Legible Trips
Bolt shows how ride-hailing is shifting from a one-tap taxi request toward a more legible, choice-driven trip, while leaving the hardest questions of price and reliability unresolved.

 Farm Land - Farming life game
Farm Land Review: A Small Island Farm with a Satisfying Loop
A bright, breezy island farm turns a few quick chores into a satisfying cycle of planting, harvesting, expanding, and deciding what to build next.

 Android Auto
’s Community Takes Shape in the Passenger Seat
Its most valuable network is not a public feed but a shared set of routes, voice habits, app integrations, and advice that make driving less isolating—and sometimes more complicated.

 My Talking Angela
 Makes the Virtual Pet Feel Personal
A polished pet-raising game built on small rituals, playful customization, and a character who gives everyday screen time a surprisingly personal rhythm.

 Google Translate
 Review: A Pocket Tool for the Small Frictions of Travel
From menus and signs to quick conversations, Google Translate earns its place by cutting the little delays that make unfamiliar language feel like a barrier.

 Shazam: Find Music & Concerts
Shazam’s Best Trick Is Turning a Song Into a Night Out
A few seconds of recognition can settle an argument, rescue a half-remembered chorus, and point toward a live show. Shazam’s real trick is what happens after the match.
Latest News



Investing Made Easy
Now, let’s talk investments. If you’re new to investing or just want a hassle-free experience, SoFi has got you covered. The app provides a wide range of investment options including stocks, ETFs, and even cryptocurrencies. Yeah, you heard me right – you can dip your toes into the crypto world without switching apps!
What I personally love is the automated investing feature. It’s perfect for those who want to invest but don’t have the time to manage their portfolio actively. You simply set your preferences, and SoFi takes care of the rest. It’s like having your own personal financial advisor who’s always available.
Choosing between an all-in-one app and separate services
The trade-off I notice with an all-in-one approach is focus. A specialist bank may suit someone who wants a narrowly tailored banking experience, while a dedicated brokerage can be a better fit for a person who wants to compare investment tools in depth. SoFi’s appeal is reducing app-switching, not necessarily replacing every specialist service. I’d choose it when convenience across several money tasks matters more than having a separate app for each one.
Automation can also make investing easier to maintain, but it does not remove the need to understand your preferences or check whether your choices still suit your circumstances. I would review those settings periodically rather than assuming a set-and-forget arrangement will always match my goals. If you prefer to choose every investment decision yourself, the automated route may feel less satisfying than a hands-on brokerage workflow.
Community and Resources
Aside from the banking and investing features, SoFi stands out with its focus on community and education. The app offers a variety of resources to help you make informed financial decisions. From webinars to articles, you can find everything you need to boost your financial literacy.
There’s also a vibrant community within the app where you can connect with other users. Sharing tips, asking questions, or even just venting about financial woes – it’s all part of the SoFi experience.
And let’s not forget about the member benefits. From career coaching to exclusive events, SoFi goes beyond being just a financial tool. It’s a community that supports you in achieving your financial goals.
Age, trust, and everyday coordination
The app is rated for Everyone, but I would still think of it as a personal finance tool for the account holder, not something to hand to a child as a way to manage household money. A general age rating is not a substitute for adult judgment about financial decisions, privacy, or who can access a device. In a household, it is safer to discuss budgets and goals openly while keeping individual account credentials private.
SoFi is a finance app from Social Finance, LLC. It is free to download, has an average rating of 4.0 from around 49,000 ratings, and has passed 5 million installs. It first appeared on April 10, 2017, and version 3.72.2 supports Android 8.0 and later. Those details suggest a well-established option, but I would still compare the account terms and investment choices with my needs before moving my main financial activity into it.
Who benefits most, and who may prefer another route
I’d recommend it to someone who wants banking and investing together, appreciates an approachable interface, and is comfortable keeping a close eye on their own financial decisions. It can also suit a busy person who wants to check savings and investments during a normal day without opening several apps. If you need a branch-centered banking relationship, highly specialized investing tools, or a purpose-built way for multiple people to manage shared household finances, a different service—or a combination of services—may fit better.
One practical approach is to start by using the app for a limited task, such as checking balances or learning how the investing section is organized, before making it central to your routine. That gives you a chance to see whether the combined layout helps you stay organized or makes the different money goals feel crowded together. I would also keep a simple record of shared bills outside personal accounts so that household coordination does not depend on one person’s login.
Putting a daily routine to the test
A realistic test is a payday routine: I would review what has arrived, leave enough in the appropriate account for upcoming personal expenses, and decide separately whether any amount is genuinely available for a longer-term goal. The benefit is having banking and investing close together; the discipline is not letting that visual proximity blur the difference between spending money and money exposed to investment risk. I would make any transfer or trade deliberately, rather than treating a quick glance at the screen as a financial plan.
For shared expenses, I would agree with a partner or roommate on the amount each person owes and the date it is due, then track that agreement somewhere both can access. SoFi can help an individual see their own finances, but a household still needs a clear arrangement for responsibilities. This is especially useful when one person handles a payment initially and the other reimburses them later: a written record avoids relying on memory or assuming the app will coordinate the two people’s accounts.
Making the combined layout work for you
The main practical question is whether you want one financial home or a collection of specialist tools. I would try SoFi first for the tasks I repeat most often, then notice whether its combined view makes me more attentive or simply gives me more sections to check. If an investment feature draws attention away from a savings goal, separating those routines mentally—or using a different service for one purpose—may be wiser than insisting that everything live together.
It is also worth checking the details of each account or investment choice before relying on a headline impression. A strong savings rate can be appealing, but the right decision still depends on the applicable account terms and how quickly you may need access to money. Likewise, an easy-to-use investing screen does not make a volatile asset suitable for short-term bills. I treat convenience as a way to support a plan, not a reason to skip the plan.
New users may reasonably wonder whether they need to move all their money at once. I would not. Starting with a narrow purpose lets you learn the app’s organization and confirm that it suits your habits before shifting more of your routine into it. It also makes it easier to spot friction: perhaps you prefer a branch relationship, want more specialized brokerage tools, or simply find that separating banking and investing helps you stay focused.
What the all-in-one approach cannot solve
Putting multiple financial activities in one app does not automatically make their rules, risks, or responsibilities identical. Bank balances, savings goals, investment choices, loans, and credit products each deserve separate attention. I would read the relevant terms when considering any product, and I would avoid assuming that a feature is right for me simply because it sits beside another feature I already use.
There is a personal trade-off, too: concentrating activity can make routine checks quicker, but it can also make the app feel like the control panel for every money decision. Someone who wants a quiet, basic checking experience may find a simpler banking app less distracting. Someone who researches investments closely may prefer a brokerage built around deeper analysis. SoFi is most convincing when reducing friction matters more than having a specialist interface for every task.
For a household, I would keep the account boundary simple: each adult manages their own credentials and decides what they are comfortable sharing, while shared plans are recorded in a place the household has agreed to use. That approach avoids implying that the app supplies joint household permissions or family oversight. It also gives younger family members a chance to talk about budgeting and saving without handing over control of an adult’s financial account.
A measured household verdict
SoFi is a useful candidate for an individual who wants everyday banking and investing within one finance app, and who values an accessible starting point over a collection of separate specialist services. Its breadth can support a practical routine, from checking personal money to reviewing investment choices, but it cannot decide how a household should divide bills or whether a particular investment fits someone’s circumstances.
I would recommend trying it if you are comfortable managing your own account boundaries and willing to review the terms and settings behind the products you use. I would look elsewhere if branch access, specialist investment research, or built-in coordination for multiple household members is central to your decision. The best arrangement may be SoFi for personal finances alongside a shared bill tracker or another service for the needs it is not designed to handle.
In conclusion, if you’re looking for a comprehensive solution to manage your finances, SoFi - Banking & Investing might just be the app for you. With its robust features, user-friendly design, and community-driven approach, it offers everything you need to take control of your financial future. Give it a try and see how it can simplify your life.
SoFi: Bank, Investing & Crypto Frequently Asked Questions
Is SoFi available on both Android and iOS?
SoFi is a finance app for mobile devices, and the version number and minimum operating-system requirement can differ by platform. The Android version is 3.72.2, while the listed minimum operating-system version is 8.0. Before downloading, check the app store on your device to confirm compatibility and view the current version available for your platform.
Who develops SoFi, and is it a well-established app?
SoFi is developed by Social Finance, LLC. It has been available since April 10, 2017, and has more than five million installs, with an average rating of 4.0 from around 49,000 ratings. Those figures offer a sense of its reach, but it is still worth reading recent user reviews and deciding whether its tools suit your own needs.
Is SoFi free to download, and what devices can run it?
SoFi is free to download and is listed for everyone. It is a finance app from Social Finance, LLC, bringing banking, investing, and saving features together. Before installing, check that your device meets the app’s operating-system requirements; the listed minimum is iOS 8.0. Once installed, you can explore the app’s available financial tools and decide which services fit your needs.
What is SoFi and what services does it offer?
SoFi is a comprehensive financial platform that provides a range of services including banking, investing, and lending. It offers features like a checking and savings account with competitive interest rates, investment opportunities, student and personal loans, as well as financial planning tools. The app aims to simplify financial management for its users by offering all these services in one place.
How secure is the SoFi app in terms of protecting my financial data?
SoFi takes security very seriously and uses state-of-the-art encryption technology to protect your personal and financial information. The app employs multi-factor authentication and regular security audits to ensure data integrity and confidentiality. Users can feel confident that their data is secure against unauthorized access and breaches.
Pros
- User-friendly interface.
- No account maintenance fees.
- Access to various investment options.
- Free ATM access worldwide.
- Fast customer support.
Cons
- Limited physical branch access.
- Some features are US only.
- High wire transfer fees.
- Limited cash deposit options.
- No joint accounts.