Payactiv
- 9.10K
- 4.4
- Installs
- 1.00M
- Price
- Free
Screenshots
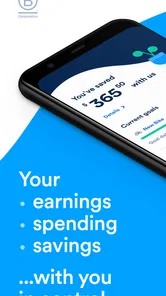
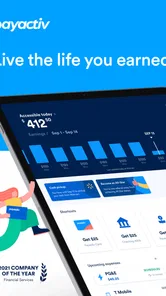
Analysis by Reviewed
I judge an early-pay app less by the relief it offers on the first urgent day and more by whether it helps without quietly becoming part of every pay cycle. Payactiv is a finance app from On-demand pay and beyond, built around access to wages you have already earned. Its appeal is clear, but I’d treat it as a flexible cash-flow tool rather than extra income: money made available early still has to cover the stretch until the next payday.
The first-week appeal
The immediate draw is easy to understand. If a bill lands before payday, seeing some earned wages become accessible can feel more useful than putting the expense on a credit card or looking for a short-term loan. The key practical condition is that your employer needs to be on board. Before relying on the app for a deadline, I’d check whether you can enroll and what access is available to you; an app cannot solve a same-day cash problem if that setup is not in place.
A realistic use is a necessary expense that cannot wait, such as replacing a work item or handling an unexpected household bill. I’d use early access for that specific gap, then make a quick plan for the remaining days before payday. That small pause matters: the money is part of your pay, not a bonus, so taking more now can leave less room later.
When an early transfer makes sense
For example, imagine a household bill is due a few days before payday and a needed replacement item for work cannot wait. I would first check which expenses remain before payday, then decide whether accessing earned wages covers the immediate need without putting rent, food, or transport at risk later in the week. This is a more useful test than asking only whether money is available: the real question is whether the timing change leaves the rest of the pay period manageable.
I would also separate urgent necessities from purchases that can wait. That is not a moral rule; it is a way to protect the feature’s usefulness. If a transfer is for something essential, the trade-off may be worthwhile. If it is for a discretionary purchase, waiting can reveal whether the desire survives after payday and avoid turning a convenience into a default spending habit.
Access to Earned Wages
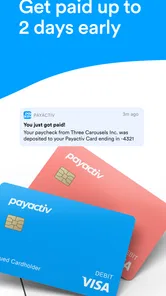
Imagine a world where you don’t have to wait two weeks for a paycheck. With Payactiv, that world is a reality. The app provides access to the wages you’ve already earned but haven’t yet been paid. This feature is a game changer, especially for those living paycheck to paycheck. It’s not about borrowing money; it’s about accessing what you’ve already worked for.
How It Works
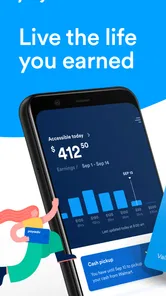
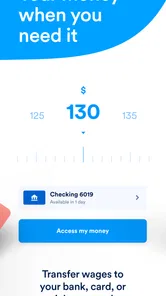
Once you’ve signed up and your employer is on board, you’re good to go. The app is intuitive and easy to navigate. You can see your available balance and transfer funds to your bank account or use them directly from the app. The process is quick, usually taking just a few minutes, which is perfect when you’re in a pinch.
More From Our News Desk

 Bolt: Request a Ride
Bolt and the Shift from One-Tap Rides to More Legible Trips
Bolt shows how ride-hailing is shifting from a one-tap taxi request toward a more legible, choice-driven trip, while leaving the hardest questions of price and reliability unresolved.

 Farm Land - Farming life game
Farm Land Review: A Small Island Farm with a Satisfying Loop
A bright, breezy island farm turns a few quick chores into a satisfying cycle of planting, harvesting, expanding, and deciding what to build next.

 Android Auto
’s Community Takes Shape in the Passenger Seat
Its most valuable network is not a public feed but a shared set of routes, voice habits, app integrations, and advice that make driving less isolating—and sometimes more complicated.

 My Talking Angela
 Makes the Virtual Pet Feel Personal
A polished pet-raising game built on small rituals, playful customization, and a character who gives everyday screen time a surprisingly personal rhythm.

 Google Translate
 Review: A Pocket Tool for the Small Frictions of Travel
From menus and signs to quick conversations, Google Translate earns its place by cutting the little delays that make unfamiliar language feel like a barrier.

 Shazam: Find Music & Concerts
Shazam’s Best Trick Is Turning a Song Into a Night Out
A few seconds of recognition can settle an argument, rescue a half-remembered chorus, and point toward a live show. Shazam’s real trick is what happens after the match.
Latest News



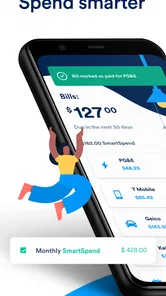
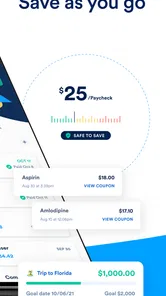
Additionally, it’s not just about accessing money. The app also features tools to help manage your budget, track spending, and even assist with savings. It’s like having a personal finance advisor at your fingertips.
What to check before depending on it
A sensible first step is to confirm that your employer participates and that your account is ready before an urgent bill appears. I would also look at the transfer choices and the timing shown in my own account, rather than assuming every route works the same way. When the deadline is close, the practical value depends on whether the option available to you fits the deadline—not simply on seeing an available balance.
That distinction is easy to overlook when an app feels straightforward. I would not build a bill-payment plan around money I have not confirmed I can access in time. For a payment with a hard due date, having a backup plan is still sensible until you know how the app fits your employer’s setup and your preferred way of receiving or using funds.
Making it useful month to month
For lasting value, I’d connect any use of early wages to a recurring budget check rather than treating each access as a fresh solution. Looking at upcoming bills first can help you decide whether an early transfer addresses a temporary timing mismatch or simply shifts the shortfall to the next week. If the same category keeps pushing you to draw wages early, that pattern is useful information: it may point to a bill date, spending habit, or income gap that deserves a longer-term fix.
This is where the app differs from a basic budgeting tool. A budget app can help you see a squeeze coming, but it does not itself make earned pay available; a credit product may cover a gap too, but that means borrowing rather than receiving wages already earned. Payactiv’s role is narrower and potentially helpful when timing is the problem. If your main need is long-term debt planning or a complete household budget, I’d pair it with a tool focused on those tasks instead of expecting one app to do everything.
How it compares with familiar alternatives
Compared with waiting for the regular payday, early wage access is useful when the calendar—not the total amount earned—is the immediate problem. Compared with a credit card or short-term loan, the basic distinction is that this app is centered on pay you have already earned rather than borrowed money. Those options are not interchangeable: borrowing may be more relevant for an expense larger than the wages available, while waiting may be better when the purchase is flexible and the next payday is close.
A conventional budget app can help identify where money is going and plan ahead, but it cannot by itself change when wages arrive. That makes the tools potentially complementary, not competitors in every situation. I would use Payactiv for a verified timing gap and keep a separate budgeting method if I need a fuller view of bills, savings goals, or debt. If the core issue is that income consistently falls short of expenses, access to pay earlier does not fix that arithmetic.
Usability and Design
The design is sleek and user-friendly. I appreciate that everything is laid out clearly, making navigation a breeze. Whether you’re a tech whiz or someone who struggles with new apps, you’ll find Payactiv easy to use. The app’s performance is smooth, with no noticeable lag or glitches during my time using it.
Moreover, the app offers multilingual support, which is a nice touch for non-English speakers. It shows that the developers are thinking inclusively, trying to cater to a broader audience.
Keeping the routine low-friction
I would make a habit of checking the available balance alongside the next payday and planned expenses, not just opening the app when money feels tight. That turns the balance into a planning cue instead of an invitation to spend. It is also worth deciding in advance what counts as a genuine reason to access wages early; a clear personal rule can reduce impulsive transfers and make the feature easier to keep in perspective.
There is a maintenance trade-off: the app can put useful information in one place, but a financial routine still depends on reviewing it and adjusting your spending. If you already track every bill in another system, adding a second place to check may create more friction than value. I’d keep whichever method gives you the clearest picture and avoid maintaining duplicate budgets just because the app offers finance tools.
A useful check-in without a second budget
To keep the routine practical, I would use the app’s balance as one input to a short check-in, not as a replacement for a complete monthly plan. Before accessing wages, I’d compare the amount I can use with the bills and essentials still due before payday, then note what the next payday needs to cover. This modest routine can show whether an early transfer is solving a one-off mismatch or making the following week tighter.
If you already manage money in a spreadsheet, banking app, or notebook, there is no need to recreate the whole system inside another tool. A quick note of the transfer and the reason for it may be enough to see a pattern over time. The useful question is not whether every feature is being used; it is whether the information you check helps you make a calmer decision.
Security Features
When dealing with financial apps, security is paramount. Payactiv doesn’t skimp in this department. The app employs robust encryption and follows industry-standard security protocols to protect your data. This gives you peace of mind knowing your information is safe.
Additionally, the app requires authentication before you can access your account, adding an extra layer of security. It’s reassuring to know that they take protecting your information seriously.
Who is likely to benefit—and who may not
I see the strongest fit for someone whose employer participates, whose pay is already earned, and whose occasional expense arrives inconveniently before payday. A worker with variable household bills might value the option as a bridge for a necessary cost, provided they can still plan for the rest of the pay period. It may also suit someone who wants a direct way to consider earned pay without turning every short gap into a borrowing decision.
It is a weaker fit if your employer is not participating, if you rarely face timing pressure, or if you would rather keep every money task inside tools you already use. Someone looking for a complete debt strategy, a long-range savings plan, or a fix for a persistent difference between income and expenses should not expect early access alone to provide it. In those cases, a budgeting or financial-counseling approach may address the underlying issue more directly.
Where it may become tiring
The main source of fatigue is not complicated navigation; it is the possibility of relying on early access so often that payday stops feeling like a reset. If using the app repeatedly leaves too little for later expenses, the convenience can disguise a cash-flow problem rather than solve it. I’d review the habit after a few pay cycles and consider a different approach if the same shortfall keeps returning.
It is also not a universal fit. Someone whose employer is not participating, who rarely needs to bridge the gap between work and payday, or who prefers to keep financial activity in a bank’s existing tools may get little lasting benefit. Before counting on it for an urgent payment, check your own access and the transfer option shown in your account; timing and availability can matter more than a smooth interface when a deadline is close.
There can be a mental cost even when the app is easy to operate: repeatedly checking what is available may keep attention fixed on short-term cash rather than the whole pay period. I would avoid opening it whenever I feel anxious about money unless I am ready to make a decision. A planned check-in is more useful than constant balance-watching, especially if seeing a number tempts me to treat it as spending room rather than pay that must last.
For some people, the better alternative is simply to move bill dates where possible, set aside a small buffer, or use an existing bank account’s planning tools. Those steps may take time and are not always available, but they can reduce the need to repeatedly shift the timing of wages. I would not force an early-pay routine just because the option exists; a tool that is rarely needed can be left unused without losing its value as a backup.
Payactiv is free to install, rated for Everyone, and has a 4.5 average from around 40,000 ratings, with over 1 million installs. It has been available since June 4, 2014, and version 2.2.2 supports devices running operating system 10 or later. Those details suggest an established app, but popularity is not a substitute for checking whether it fits your employer and your own pay routine.
Questions worth settling in your own account
Before making it part of a regular plan, I would answer a few practical questions by checking the account itself: Can I enroll through my employer? What amount is available to me at the moment I need it? Which way of using or receiving that money suits the expense, and will it arrive in time? These checks are more useful than assuming the same experience applies to every worker.
I would also ask myself what happens to the next stretch of the budget after a transfer. If the answer is clear and manageable, the feature may be doing its job. If the answer is that another bill will probably require another early transfer, that is a signal to pause and look at the pattern, rather than treating another access as an automatic solution.
In conclusion, Payactiv is more than just a financial app; it’s a lifeline for those who need a little extra flexibility with their finances. Whether you’re dealing with an unexpected car repair or just need some extra cash before payday, this app is worth considering. It’s designed with the user in mind, providing both functionality and security. If you’re looking for a way to access your earned wages without the stress of waiting, give Payactiv a try. It might just be the financial partner you didn’t know you needed.
My long-term verdict
I’d keep it installed if early wage access solves an occasional, specific timing problem and I can still plan comfortably for the next payday. I would not treat it as a substitute for an emergency fund or as a reason to spend more freely. The app earns lasting space when it supports a deliberate routine; if it becomes a repeated patch for the same shortfall, stepping back and choosing a broader budgeting or debt-management approach is the better move.
Payactiv Frequently Asked Questions
Can I check whether my employer offers Payactiv before I download it?
Yes. Payactiv’s wage-access features are intended for employees whose companies offer the service, so checking with your employer or HR team is a useful first step. The app may not provide the same practical value if your company does not participate. If it is available through your workplace, you can then consider whether its early wage access and financial wellness tools suit your needs.
What should I consider before using early access to my wages?
Early access can make wages you have already earned available before payday, which may help when an expense comes up. It is still important to plan around your normal pay cycle: money accessed early will affect what remains for payday. Think about whether using this feature supports your budget and financial goals, rather than treating it as additional income.
What does Payactiv’s Everyone age rating mean for prospective users?
Payactiv is a finance app with an Everyone content rating, so its age classification is broad. That does not mean every person can use its wage-access features: access depends on whether an employer offers Payactiv. Consider both the app’s age rating and your employer’s participation before deciding whether it fits your needs.
Which devices can run Payactiv, and is it suitable for everyone?
Payactiv is available for Android and iOS, and its minimum operating-system requirement is version 10. Check your device’s software version before downloading to make sure it meets that requirement. The app may be useful to employees whose companies offer Payactiv, but it is not necessarily suitable for someone whose employer does not participate.
What is Payactiv and how does it work?
Payactiv is a financial wellness and benefits platform that provides employees with access to earned wages before their payday. It works by allowing users to access their earned income anytime during the pay cycle, helping them avoid overdraft fees, payday loans, and high-interest credit card debt. Users can access their funds through the app and manage their finances more effectively with budgeting tools and financial counseling.
Pros
- User-friendly interface for easy navigation.
- Provides real-time access to earned wages.
- Integrates with various payroll systems.
- Offers financial wellness tools and resources.
- Available on both Android and iOS platforms.
Cons
- Limited to employees of participating companies.
- Requires stable internet connection.
- Some features may have additional fees.
- Customer support can be slow at times.
- May require employer setup for full access.