Rocco - Fast Cash Advance
- 1.38K
- 4.2
- Installs
- 100.00K
- Price
- Free
Screenshots
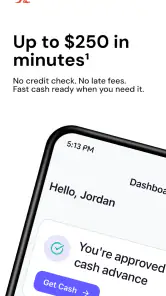
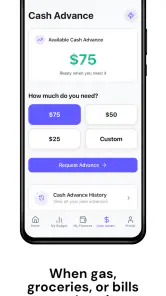
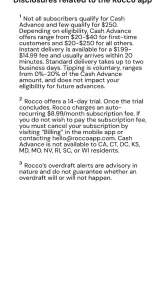
Analysis by Reviewed
I approached Rocco - Fast Cash Advance as a practical finance app rather than a general budgeting tool. Its focus is clear: it connects cash-advance services with personal-finance needs, so the important question is not whether it looks impressive, but whether it helps you handle a short-term money gap without adding confusion. My experience is that the app is most useful when you already know exactly why you need the money and can review every repayment detail calmly before accepting anything.
Rocco is free to download, aimed at Everyone, and developed by Rocco Finance, Inc. It has reached over 100 thousand installs and holds a 4.2 average from around 4 thousand ratings, with roughly 1.4 thousand written reviews. Those figures suggest that it has found a real audience, although they should not be mistaken for a guarantee that every applicant will receive an advance or have the same experience.
How Rocco feels when you need an answer quickly
The strongest part of the app’s appeal is its direct purpose. When an unexpected bill appears between paydays, opening a finance app that is specifically built around cash advances feels more practical than searching through a full banking platform. Rocco keeps the idea of short-term assistance at the center, which makes the first step easier to understand for someone who does not want to learn a complicated financial dashboard.
That said, “fast” should be treated as a description of the intended experience, not a promise that money will appear immediately. The pace of any advance depends on the information you provide, eligibility checks, and the terms presented during the process. I would not open Rocco expecting it to replace an emergency fund or function like an instant transfer button. It is better viewed as a way to explore a possible short-term option.
My advice is to begin with a specific amount and a specific repayment plan in mind. If you open the app while feeling pressured and simply choose the largest available option, the convenience can work against you. A smaller advance that solves the immediate problem is generally easier to manage than borrowing extra money for unrelated spending.
The most important speed tip is to prepare before you apply. Have the details you normally need for a financial application close at hand, read each screen instead of tapping through it, and allow time to inspect the total obligation. This makes the process feel faster because you avoid stopping halfway to find information or reconsider a term you did not notice.
A realistic payday-gap scenario
Imagine that your car needs an urgent repair a few days before your next paycheck. You open Rocco, review the available cash-advance path, and compare the amount you need with what you can comfortably repay. In that situation, the app may be useful because it puts the relevant decision in one place instead of making you call several providers or navigate a traditional loan application designed for larger borrowing.
The responsible version of this scenario includes a second step: checking your next pay cycle after the advance is repaid. If the repayment would leave you short for rent, groceries, or utilities, the advance has only moved the problem forward. Rocco can help with timing, but it cannot make an unaffordable repayment affordable.
What happens during heavier use
Finance apps are not usually demanding in the same way as games or video editors. Rocco is designed for forms, account information, and financial decisions, so I would expect the meaningful workload to come from moving through the application process rather than from long periods of screen-heavy activity. That is a positive distinction: you are unlikely to need a powerful phone simply to use its central purpose.
The more important “heavy-use” moment is when you revisit the app repeatedly to monitor a pending request, check a repayment-related detail, or compare an advance with another option. In those situations, the app’s value depends on clarity and consistency. A clean screen is helpful, but it should never encourage rushed decisions. I prefer to use it in a quiet moment, with my regular expenses visible, rather than while standing in a checkout line or dealing with the emergency itself.
There is also a practical trade-off between convenience and attention. Because the app is focused on cash access, it can make borrowing feel more immediate than opening a spreadsheet or speaking with a bank. That is not automatically bad, but it means I would use Rocco alongside a simple personal budget rather than as my only financial planning tool.
Stability matters more than visual polish
With a finance app, reliability means more than whether the interface opens quickly. I want each step to be understandable, the information I enter to remain consistent, and the final terms to be easy to review before I commit. Rocco’s dedicated purpose gives it an advantage over a cluttered all-in-one finance app, because there are fewer unrelated tools competing for attention.
Still, I would not treat a successful application screen as the end of the process. Save or note the relevant repayment information in a secure place, check your bank activity separately, and keep any confirmation messages you receive. This is a useful habit with any cash-advance service, but it is especially important when you are using a mobile app during a stressful situation.
If the app pauses, closes, or behaves unexpectedly, I would avoid repeatedly submitting the same request. First check whether the previous attempt was recorded, then reopen the app and review the status. Repeating actions too quickly can create uncertainty about what was actually submitted. That recovery approach is less exciting than simply tapping again, but it is safer for a financial workflow.
The app’s current version is 3.0.0, which indicates that it is not an untouched first release. I see that as a modest positive for maturity, but not as proof that every device or application path will behave perfectly. Version numbers can show ongoing development; they cannot replace careful checking of the screen in front of you.
Phone requirements and everyday device limits
Rocco supports devices running Android 8.0 or later, so anyone using an older Android phone should check compatibility before planning around it. For a finance app, this requirement is fairly approachable, but older compatible hardware can still bring practical limitations such as slower app launches, limited free storage, or an operating system that no longer receives regular security improvements.
I would avoid using a shared or poorly secured phone for sensitive financial activity whenever possible. A newer device is not automatically safer, but an up-to-date operating system, a screen lock, and a private connection make more sense than relying on an old handset that struggles with basic app tasks. If your phone is nearly full, close unrelated apps and clear enough space before starting an application; interruptions are particularly inconvenient when you are entering personal information.
Rocco is also not the kind of app I would install on a tablet or spare device simply because there is room for it. The best device is the one you control and protect regularly. After using it, lock the screen and avoid leaving financial pages open where another person can see them. These are simple habits, but they matter more here than squeezing out a few seconds of launch time.
Where it fits beside normal alternatives
Compared with asking a bank about a personal loan, Rocco is more narrowly focused and may feel less intimidating for a small, short-term need. A traditional bank can be a better choice when you need a larger amount, a longer repayment period, or a relationship-based review. It may also be preferable if you already have an established overdraft arrangement or another clearly understood emergency option.
Compared with borrowing from someone you trust, Rocco offers a more formal and private route, but a personal arrangement may be less complicated if the people involved can agree on repayment without pressure. Compared with a credit card, a cash advance can appear simpler for a single gap, while a credit card may offer more flexibility for someone who already understands its interest and payment structure. Neither comparison makes Rocco universally better; the right choice depends on the total cost, timing, and consequences of repayment.
I would also separate Rocco from a budgeting app. A budgeting app helps you understand where money goes and plan ahead. Rocco is aimed more at the immediate cash-flow problem. If your shortfall happens every month, using an advance repeatedly is a warning sign that the underlying budget needs attention. In that case, a spending review, a conversation with a creditor, or a longer-term financial plan is likely more useful than another short-term solution.
Small details that improve the experience
One useful workflow is to calculate the gap before opening the app. Write down the bill, the amount already available, and the amount your next paycheck must cover. Then use Rocco only to investigate the remaining difference. This prevents the app from becoming a place where you discover how much you can borrow before deciding how much you should borrow.
A second good habit is to read the repayment information twice: once before accepting an option and again after the request is complete. The first reading supports the decision; the second confirms that your understanding matches the final screen or record. I would pay particular attention to timing and the total amount due, not just the amount deposited.
A third insight is to keep Rocco as an emergency tool rather than a routine spending companion. If you use it only when a genuine timing problem appears, it is easier to judge whether the service solved a specific issue. If you open it whenever your balance feels uncomfortable, the convenience can hide a growing pattern of dependence.
Finally, do not confuse the app’s free download with the advance itself being free. The fact that the app costs nothing to install says nothing by itself about the terms of a financial product. Review the complete offer shown to you, including any repayment obligation, before making a decision. That distinction is essential and is easy to overlook when you are focused on speed.
Who should use it, and who should skip it
I think Rocco is worth considering for an adult who needs to investigate a short-term cash-flow option, understands the difference between an advance and income, and can identify a realistic repayment source. It may also suit someone who prefers handling the first stage from a phone instead of contacting several financial providers directly.
I would skip it if you are looking for a full budgeting system, investment tools, long-term debt planning, or a guaranteed emergency fund. I would also be cautious if your next paycheck is already committed, if you are considering an advance for discretionary purchases, or if you are applying without understanding the final repayment amount. In those situations, the app’s convenience is not enough to offset the financial risk.
Because the app is rated for Everyone, it is broadly presented as suitable for a general audience, but that does not mean every financial decision inside it is suitable for every person. Younger users and anyone unfamiliar with borrowing should involve a trusted adult or financial adviser before accepting an advance. The age label describes app access, not personal affordability.
My overall performance verdict
After looking at Rocco through the lens of speed, stability, device demands, and recovery, I see a focused tool with a sensible place in the finance category. It should be light enough for ordinary Android phones that meet its system requirement, and its narrow purpose is easier to understand than a crowded financial super-app. The strongest performance benefit is not flashy animation or complex automation; it is the reduced distance between recognizing a short-term cash problem and reviewing a possible solution.
Its main weakness is also tied to that focus. A specialized cash-advance app can make borrowing feel like the obvious next step, even when better options exist. The app cannot decide whether the repayment will disrupt your budget, and no smooth mobile experience removes the need to inspect the terms. I would therefore judge it by the quality of my decision after using it, not merely by how quickly I reached an application screen.
My recommendation is conditional: use Rocco as a carefully checked emergency option, not as a substitute for planning. The free app, broad device support, and established presence make it reasonable to explore when a genuine payday gap appears. But I would compare the repayment obligation with alternatives, borrow only what solves the immediate problem, and keep a record of what I agree to.
For someone who wants a dedicated route to cash-advance and personal-finance services, Rocco - Fast Cash Advance is a practical app to investigate. For someone whose money troubles are recurring, whose repayment plan is uncertain, or who wants comprehensive financial management, a bank, budgeting service, or longer-term adviser may be the better fit. Used with that distinction in mind, Rocco can be useful without pretending to be a complete answer to every financial problem.
Pros
- Simple application process with minimal paperwork
- Fast eligibility checks can help in urgent situations
- Clear repayment details are shown before accepting an offer
- Useful for comparing available advance amounts
- Mobile access lets you manage requests from almost anywhere
Cons
- Cash advances may include high fees or expensive borrowing costs
- Approval and terms can vary based on location and credit profile
- Repayment may be required soon after receiving the advance
- Late payments could lead to additional charges or account issues
- Availability and lending options may be limited in some states
- Category
- Finance
- Version
- 3.0.0











