Rain Instant Pay
- 3.79K
- 4.8
- Installs
- 500.00K
- Price
- Free
Screenshots
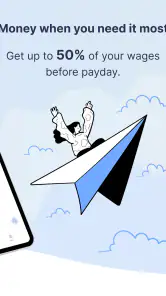
Analysis by Reviewed
I see Rain Instant Pay as a tool for changing the timing of pay, not increasing the amount you earn. That distinction matters: getting access to wages earlier can help with a bill that arrives before payday, but it doesn’t make a tight monthly budget less tight. Used for a specific short-term gap, it may be useful; treated as extra income, it can leave the next pay period feeling smaller.
Check the employer connection before counting on it
The first practical question is whether your workplace is partnered with Rain. That makes the app less like a general cash advance service and more like a benefit tied to your employment. If you’re considering downloading it, I’d ask HR or check your employer’s benefits information first, rather than planning around money you may not be able to access. A change of employer can also change whether the service is available to you.
Rain Technologies Inc makes this business-focused app, which is free to install and rated for Everyone. Its current version is 1.77.1, and the 7.1 minimum OS requirement makes it relevant to people using older compatible devices. It has a 4.8 average from around 30,000 ratings, with about 3,800 written reviews and over 500,000 installs. Those figures suggest plenty of people have tried it, but they don’t tell me whether it fits every employer’s payroll setup or every worker’s needs.
How early wage access fits into real life
If you’ve ever found yourself in a pinch, waiting for payday to come faster, you’re going to want to lend me an ear because I’ve got the scoop on a game-changer! Meet Rain Instant Pay, the app that’s making waves by letting you access your hard-earned cash anytime you need it. As someone who’s always trying to make ends meet, I decided to dive into this app to see if it lives up to the hype. Spoiler alert: it does, and I'm here to tell you all about it.
What’s the Deal with Rain Instant Pay?
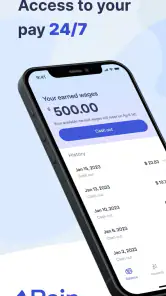
Alright, folks, let’s break it down. Rain Instant Pay is essentially a financial lifeline for those unexpected moments when your wallet feels a little too light. The app allows you to access a portion of your earned wages before your scheduled payday. No more waiting in agony while your bills pile up! You just work, earn, and tap into your available funds when you need them.
How It Works
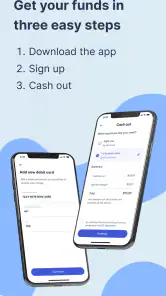
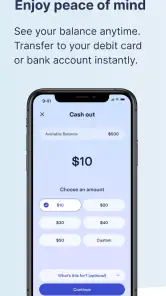
The magic of Rain Instant Pay lies in its simplicity. First off, your employer needs to be partnered with Rain, but once that’s set, it’s smooth sailing. You earn your wages as usual, and Rain tracks the hours you’ve worked. When you find yourself needing a little cash infusion, you simply request the amount you need through the app, and voila! It’s straight into your bank account within minutes. The app is user-friendly, with a clean interface that makes navigation as easy as pie.
In everyday use, I’d treat the available balance as a ceiling, not a spending target. If a grocery run or a utility bill falls awkwardly before payday, check the amount you actually need and consider how that withdrawal will affect the money left for later. A small, planned transfer for a defined expense is easier to account for than repeatedly dipping into wages because the balance happens to be there.
More From Our News Desk
Clash of Clans Is Won Between the Battles
Android Auto Makes the Case for Quieter Car Software
MobiOffice: Transforming Mobile Productivity with Seamless Integration
EA SPORTS FC™ Mobile Soccer: Redefining Mobile Sports Gaming
How Microsoft OneDrive Became a Mobile Productivity Giant
How Google Translate Breaks Language Barriers Effortlessly
Why You Might Love It
Let’s get real for a second. Life throws curveballs, and sometimes those curveballs come with a price tag. The ability to access your cash whenever you need it without the hassle of traditional payday loans or credit checks is a huge plus. Plus, it could save you from overdraft fees or the embarrassment of borrowing from friends and family. It’s like having a financial safety net right in your pocket.
A useful option, not a replacement for budgeting
For example, imagine a necessary expense lands a few days before payday and you would otherwise risk a late payment. Early access may give you another way to bridge that timing gap. But it’s worth checking the terms shown in the app before requesting money, including any cost associated with the transfer, and comparing that with the consequence of waiting or using another payment method. The right choice depends on the particular bill and your next pay cycle.
Compared with a traditional payday loan, Rain is connected to wages you have already earned rather than a new loan arranged independently of your employer. That can make the idea easier to understand, but I wouldn’t assume every transfer is free or that repeated use has no effect on cash flow. A bank overdraft or a credit card may be preferable for someone who can repay it on a clear schedule and has favorable terms; for someone trying to avoid borrowing, waiting until payday may be the better choice.
Potential Drawbacks
Now, while I’m all about the positives, it’s only fair to mention a couple of things to watch out for. Depending on your usage, there may be fees associated with accessing your funds, so it’s crucial to be mindful of how often you’re using the service. Also, if your employer isn’t on board with Rain, you won’t be able to use it. So, a little heads up to check with your HR department could save you some disappointment.
What to consider before relying on it
One useful habit is to decide in advance what counts as a genuine reason to use early pay, such as an essential expense with a firm deadline, and what can wait. That personal rule can prevent convenience from turning into a routine that shifts the same shortage from one part of the month to another. I’d also leave room for the possibility that the amount available depends on wages already earned, so it may not cover an entire unexpected bill.
If a transfer does not appear to match your expectations, check your work hours and the amount displayed before making plans around it. The app depends on the employer relationship and wage information, so it is sensible to resolve a payroll or eligibility question through the appropriate workplace channel rather than assuming a displayed estimate is the same as take-home pay. That small check can help avoid a last-minute scramble.
Who gets the most value from Rain
I think it suits workers whose employer offers Rain and who occasionally need a controlled way to manage a mismatch between when expenses are due and when wages arrive. It is less compelling for someone who needs a long-term answer to bills consistently exceeding income, or for anyone whose employer is not connected to the service. In those situations, a broader budget review, direct conversation with a bill provider, or another option with clearer costs may be more useful than accessing pay early.
Final Thoughts
At the end of the day, Rain Instant Pay is a solid option for anyone looking to gain a bit more control over their finances. It’s convenient, easy to use, and offers a sense of financial security that’s hard to beat. Whether you’re dealing with unexpected expenses or just want the peace of mind that comes with knowing your money is accessible, Rain has got your back. Just remember to use it wisely, and it could very well be your new best friend in financial management.
My recommendation is to think of it as a timing tool with boundaries: confirm your employer participates, review any transfer cost, and request only what solves the immediate problem. Rain was released on February 1, 2020, and its current version is 1.77.1. If those practical checks fit your situation, it can be a handy workplace benefit; if you need more income rather than earlier access to earned wages, it is not the answer.
Make the request fit the actual bill
One way I’d keep the benefit manageable is to begin with the expense, not the balance Rain makes available. If a bus pass, prescription, or grocery top-up is the immediate problem, work out the minimum amount that resolves it and stop there. This keeps the decision tied to a specific need instead of letting an available balance quietly become part of ordinary spending. It also makes the effect on the next pay period easier to anticipate.
A realistic example is a household bill due just before payday while the household still has enough food and transport money for the week. I would compare the fee and timing shown for a Rain transfer with any late charge or other consequence of paying late. If the transfer costs more than the likely downside of waiting, waiting may be the sensible choice. If the deadline is firm and the cost is lower, taking only the needed amount may be a reasonable bridge. The calculation is personal, so I would make it before tapping through rather than after.
Keep the rest of payday visible
Early access can make an urgent payment feel solved while concealing the fact that the same wages will not be available again on payday. I’d note the amount taken somewhere I already track bills, then treat it as money already spent when planning the rest of the pay cycle. This is especially helpful when several expenses cluster together: the first small withdrawal can seem harmless, while a second one may leave too little room for rent, food, or scheduled payments later.
That approach also gives a useful test of whether the app is helping. If a one-off early transfer prevents a costly timing problem and the following pay period remains workable, it has served its purpose. If I find myself using it for routine costs every cycle, I’d take that as a prompt to revisit bill dates, spending priorities, or income needs instead of relying on the same early-pay solution indefinitely.
What to check when setting expectations
A common question is whether downloading the app alone is enough to start using it. In practice, the important first step is employer participation; without that connection, it is not a general-purpose way to draw cash. I’d confirm eligibility before entering the process and avoid treating a successful installation as confirmation that wages will show up. The workplace relationship is central to how this benefit works.
Another practical question is how quickly money will arrive. The original description of the experience suggests a rapid transfer, but I would still read the timing and any charge shown for the particular request rather than building a plan around an assumed arrival time. When a payment deadline is close, leave enough margin for the method and timing available to you, and keep a backup plan if the bill cannot wait.
How it differs from other ways to cover a gap
Rain occupies a narrower lane than a budgeting app: it can help move access to earned wages forward, but it does not organize spending, negotiate a bill, or create additional income. A budget or calendar is better for spotting recurring shortfalls before they happen. A conversation with a service provider may help when the real issue is a due date, while a savings buffer can handle irregular costs without pulling future wages forward. Those alternatives take different effort, but they may address the cause rather than the timing.
It is also different from borrowing on a card or through a conventional loan. Those options create repayment obligations with their own terms, whereas Rain is framed around wages already earned through a participating employer. That distinction does not automatically make one choice cheaper or better: I’d compare the actual costs, deadlines, and effect on cash available later. If I needed a larger sum than my earned wages could cover, Rain would not solve that problem, and I would look at safer alternatives rather than assume the app could stretch further.
Who should pass, and who may find it handy
I would skip Rain if my workplace does not offer it, if I needed dependable access to money beyond the wages I have already earned, or if I knew that taking pay early would leave essential expenses uncovered later. It is also a poor fit if I am looking for a complete financial-planning tool. Its value is much more specific: a participating worker can use it to manage an occasional mismatch between a pay schedule and a necessary expense.
For someone with irregular costs but a generally workable budget, the app may offer a practical extra option when a bill lands at an awkward time. I’d still keep a small personal rule around use: check eligibility, verify the displayed amount, review transfer terms, and decide how the next payday will look afterward. That process is less exciting than tapping for money, but it is what turns early access into a considered choice rather than a reflex.
Rain Instant Pay Frequently Asked Questions
Does Rain Instant Pay work if my employer has not enrolled?
Rain Instant Pay is built around employer-provided benefits, so it is not a general-purpose wage-access service that anyone can join independently. Before downloading, check with your employer or HR team to see whether Rain is available at your workplace. If your employer has not enrolled, the app’s main benefit may not be accessible to you.
What is the age rating for Rain Instant Pay, and is it intended for personal or workplace use?
Rain Instant Pay has an Everyone content rating, but its purpose is connected to workplace benefits rather than general personal banking. The app is intended for employees whose employers make Rain available, so the age rating alone does not establish eligibility to use its wage-access features. Consider both the rating and your employer’s participation before installing.
Is Rain Instant Pay free to download, and what should I know before installing it?
Rain Instant Pay is a free business app from Rain Technologies Inc. Its purpose is to help users unlock employer benefits, so downloading it is only the first step: whether its wage-access features are useful to you depends on your workplace’s participation and the options available through your employer. The app is rated for Everyone, and it has a 4.8 average from around 30K ratings.
What is Rain Instant Pay and how does it work?
Rain Instant Pay is a financial application designed to provide employees with early access to their earned wages before the official payday. Users can request a portion of their earned wages through the app, which is then transferred directly to their bank account or provided via a physical or virtual card. This service can help users manage financial emergencies and avoid high-interest payday loans.
Is there a fee for using Rain Instant Pay?
Yes, there is usually a small fee associated with each transaction when you withdraw funds using Rain Instant Pay. The fee structure varies depending on the service agreement with your employer and the amount you choose to withdraw. It is advisable to check the app for specific details on the fees applicable to your transactions.
Pros
- User-friendly interface
- Instant payment processing
- Secure transactions
- 24/7 customer support
- Low transaction fees
Cons
- Limited to certain regions
- Requires stable internet
- Not compatible with all banks
- Occasional app glitches
- Limited currency options
- Category
- Business
- Version
- 1.77.1