Cash Advance Loan - CREDO
- 861.00
- 4.6
- Installs
- 100.00K
- Price
- Free
Screenshots
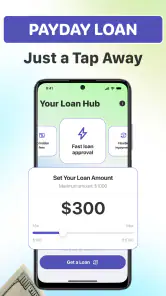
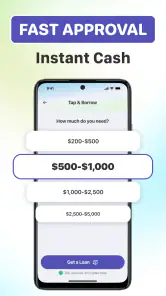
Analysis by Reviewed
When an unexpected bill lands between paydays, the hardest part is often not finding a borrowing app but understanding what you are agreeing to before you tap through an application. I spent time with Cash Advance Loan - CREDO as a finance app built around quick access to borrowed money, and my main impression is that it is most useful when treated as a short-term planning tool rather than an everyday solution. The interface is aimed at people who want to explore an advance without starting with a traditional credit-check process, but speed should not replace careful reading.
The app is free to download and is rated for Everyone, which makes the first step approachable. It comes from Same Day Fin LLC and has reached over one hundred thousand installs, with a 4.6 average from roughly twenty-one thousand ratings. Those figures suggest that many people have found the app worth trying, although popularity should never be confused with guaranteed approval or a low-cost borrowing decision.
How I approached a cash request in CREDO
The most sensible workflow begins before opening the app. I would first write down the exact amount needed, the date the expense must be handled, and the date on which repayment would realistically fit my budget. That small preparation matters because an instant cash advance can feel deceptively simple when the real question is whether the next paycheck can absorb it without creating another shortfall.
Inside CREDO, I would keep the process focused on the request rather than browsing casually. Read each screen from top to bottom, check the wording around repayment, and avoid treating a prequalification-style result as money already in your account. A request can involve eligibility checks, identity details, disclosures, and a final agreement, so I would not accept anything until the full cost and repayment timing are clear.
One useful habit is to take a moment after entering personal information and review every field before continuing. A wrong income figure, outdated contact detail, or mistaken bank entry can slow down a financial application. This is not a glamorous tip, but it is more valuable than rushing through the form simply because the app emphasizes immediacy.
The store summary presents the service as a way to borrow money instantly, including an option that does not rely on a conventional credit check. I see that as an access feature, not a promise that every applicant will receive funds. People with thin credit histories may appreciate having another route to explore, while people with strong credit should still compare the total repayment cost with a bank, credit union, overdraft facility, or an existing card benefit before choosing a short-term advance.
A realistic example would be a car repair needed to keep commuting to work. I might use the app to investigate whether an advance could cover the immediate gap, then compare the proposed repayment with the amount left after rent, utilities, food, and transport. If repayment would leave me borrowing again before the month ends, the advance would not solve the problem; it would only move the pressure forward.
What I would check before accepting anything
The most important screen is not the first approval-style message. It is the disclosure that explains how much is borrowed, what must be repaid, when repayment is due, and whether any charges apply. I would save those details for my records and compare them with the amount that will actually leave my account. A small-looking fee can become significant when the borrowing period is short.
I would also distinguish between an application, an offer, and a completed transfer. Finance apps often guide users through several stages, and those stages should not be treated as interchangeable. CREDO is best used with the assumption that eligibility and funding are separate decisions until the app clearly confirms otherwise.
Another practical step is to make a repayment calendar immediately. Put the due date in your phone, but also note the amount and the account from which it will be taken. If the app or lender presents an automatic repayment arrangement, make sure the account will contain enough money without sacrificing essential bills. A missed repayment can create more stress than the original emergency.
I would not use a cash advance to fund a purchase that can wait, cover recurring entertainment, or patch a budget that is short every month. The app may make access feel easier than a conventional loan application, but convenience does not change the underlying obligation. For repeated shortages, a spending review, payment arrangement with the biller, employer-based advance, or nonprofit financial counselor may be a better direction.
Settings and phone habits worth checking
CREDO is running as version 0.11.2 and supports Android starting with version 7.0. Before relying on it during an emergency, I would check that the phone is updated enough for the app, that notifications are enabled, and that the device has a secure screen lock. These are simple checks, but they reduce the chance of missing an important status message or leaving financial information exposed on a shared phone.
I would also review notification behavior rather than allowing every alert to appear openly on the lock screen. Financial messages can contain sensitive context. A safer setup is to receive alerts while limiting the amount of detail visible before the phone is unlocked. That is a phone-level privacy habit rather than a claim about a special CREDO setting, and it is worth doing whenever an app handles identity or banking information.
Keep the app updated through the normal app-store process, especially because this is a relatively new product with a release date of September 29, 2025. Newer versions can change screens or improve reliability, so instructions remembered from an earlier session may not match what appears later. I would never assume that a familiar button still has the same position or wording after an update.
For privacy, I would read the permission prompts and only continue when I understand why a requested access is relevant to the application process. I would avoid entering financial information while connected to an unfamiliar public network, and I would not share verification codes with anyone who contacts me claiming to represent the service. Those precautions are especially important because a fast-loan context can make people more vulnerable to impersonation and rushed decisions.
A repeatable setup helps: use one secure email address for financial services, keep your contact information current, and store the agreement in a private location. This makes later checking easier if you need to confirm repayment details. It also prevents the common mistake of searching through messages at the last minute to discover when an obligation is due.
Faster patterns that do not sacrifice judgment
Experienced users can make the process faster without turning it into a blind tap-through. My preferred pattern would be to prepare the basic information first, decide the maximum amount that fits the budget, and stop immediately if the displayed terms exceed that limit. Setting the ceiling before applying is important because the available amount can influence emotions once it appears on screen.
I would use a short comparison checklist every time:
- How much money would arrive?
- How much would leave my account in total?
- What is the exact repayment date?
- Would repayment interfere with essential expenses?
- Is another option cheaper or less risky?
This checklist is deliberately plain. It prevents the word “instant” from becoming the only feature that matters. If a bank account already offers an arranged overdraft, or if a service provider can move a bill date, those options may be less expensive and easier to manage. If a credit union offers a small emergency loan, comparing the full repayment rather than the advertised speed is the more responsible choice.
Another efficient pattern is to separate research from acceptance. On the first pass, I would learn how the application works and note what information it requests. On the second pass, only after checking my budget, I would decide whether to continue. This avoids making a borrowing decision while tired, worried, or distracted by an urgent expense.
I would also keep screenshots or written notes of the final terms, but I would not store them in an unprotected gallery or send them through casual chat. A private note with the amount and due date is enough for budgeting. The aim is to create a reliable record, not to duplicate sensitive documents everywhere.
Where the convenience reaches its limits
The biggest limitation is inherent in the product category: a cash advance solves timing, not affordability. If income does not cover normal expenses, borrowing again can create a cycle that an attractive application flow cannot fix. This is the point at which I would skip CREDO and look for a longer-term budget solution, negotiated payment terms, or independent debt advice.
The no-credit-check angle also needs careful interpretation. It may make the app relevant to someone who has limited traditional credit history, but it does not remove the need to assess repayment ability. It may also mean that the user must pay closer attention to other eligibility factors and the eventual terms. I would never assume that bypassing a conventional credit check means the advance is automatically safer or cheaper.
Speed can be another source of friction. A fast application is helpful when a genuine emergency is unfolding, but it can encourage decisions made without comparing alternatives. If the expense is not urgent, waiting long enough to check a bank, employer, bill provider, or local assistance option is usually worthwhile. The best use case is a clearly defined, temporary gap with a credible repayment plan.
Privacy and data entry are practical limits too. Anyone uncomfortable providing financial or identity information through a mobile application should choose a provider whose process they understand and trust. I would also avoid using the app on a device controlled by someone else, even if the need feels urgent.
People looking for a conventional installment loan, a long repayment period, or detailed credit-building support may be better served elsewhere. CREDO’s appeal is immediacy and accessibility, not a substitute for every kind of borrowing. Likewise, someone who only wants a budgeting tool should not choose a borrowing-focused app when a dedicated expense tracker would address the real need without creating debt.
My verdict after using it as a planning tool
Cash Advance Loan - CREDO makes the most sense for a user facing a specific, short-lived cash gap who is willing to inspect the terms carefully and budget the repayment before accepting an offer. Its free access, Everyone age rating, and focus on instant advances make it easy to consider, while its support for Android 7.0 and later keeps it usable on many older devices. Same Day Fin LLC has positioned it as a straightforward finance option, and the strong average rating shows that it has attracted positive attention.
My recommendation is conditional rather than automatic: use it as a comparison point, not as the first answer to every money problem. The repeatable workflow is simple—define the gap, check the complete repayment, compare alternatives, record the due date, and accept only what the next budget can handle. That approach preserves the app’s main benefit, speed, without allowing speed to make the decision for you.
For a one-off emergency such as an essential repair or an overdue necessity, it may be worth exploring. For recurring bills, discretionary spending, or a budget that is already permanently underwater, I would skip it and seek a more durable solution. In my view, the real strength of CREDO is controlled convenience, not effortless borrowing: it can shorten the path to an option, but the user still has to decide whether that option is genuinely affordable.
Pros
- Simple application process with clear eligibility requirements.
- Fast response can help cover unexpected short-term expenses.
- Loan details and repayment terms are shown before acceptance.
- Convenient mobile access eliminates the need to visit a branch.
- Useful repayment reminders can help users avoid missed due dates.
Cons
- Interest and service fees may make borrowing expensive.
- Short repayment periods can create pressure on limited budgets.
- Approval and loan amounts may vary by applicant and location.
- Late payments could lead to additional charges or credit issues.
- The app may request sensitive personal and financial information.
- Category
- Finance
- Version
- 0.11.2











