Cash Advance: Get 250 Fast
- 983.00
- 4.7
- Installs
- 100.00K
- Price
- Free
Screenshots
Analysis by Reviewed
I approached Cash Advance: Get 250 Fast as a practical finance app rather than a general budgeting tool, and that distinction matters. Its purpose is narrow: it is designed to help users explore a payday loan or cash advance through a simple mobile process. In my experience, the appeal is the reduced friction. You are not opening an account to track spending, build a budget, or learn about investing; you are looking for a short-term borrowing option and want the first steps to feel manageable.
The app is free to install, carries an Everyone content rating, and comes from KOMPANIIA LORENS PP. It has attracted over one hundred thousand installs and holds a 4.7 average from around twenty-five thousand ratings, which suggests that many people find the basic experience approachable. Still, a strong store score should not be confused with a low-cost loan or guaranteed approval. My central view is simple: this can be a convenient starting point for someone comparing emergency cash options, but it should be treated as a borrowing gateway, not as free money or a replacement for financial planning.
What the app does well when money is tight
The clearest strength is focus. Many finance apps surround a user with charts, account connections, spending categories, and long-term goals. That can be useful, but it is not what someone needs when a bill is due before payday. This app keeps its attention on the cash advance journey, making it easier to decide whether the product is relevant before spending time on unrelated financial tools.
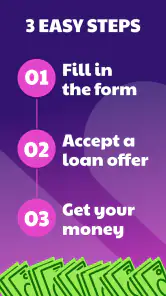
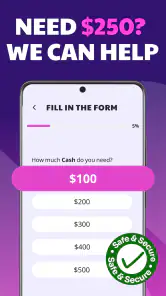
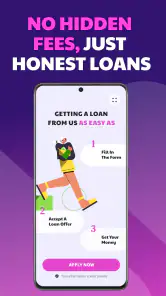
I also like the way the experience is framed around steps rather than financial jargon. A person who has never used a cash advance service may feel uncertain about where to begin, especially when dealing with an urgent expense. A straightforward flow can reduce that initial anxiety. The best use of the app is therefore not rushing through every screen, but using the guided process to understand what is being requested and what the next decision involves.
That simplicity is particularly useful on a phone. If I were checking options during a lunch break or while dealing with an unexpected household expense, I would value an interface that lets me review the process without needing a desktop computer. The app’s current version is 1.2.2 and supports Android 7.0 or later, so it is accessible on a broad range of older Android devices as well as newer phones.
One practical advantage is that the app can serve as a screening tool before a borrower commits to anything. I would use it to ask myself several questions in order: How much do I really need? When could I repay it? What total amount would repayment involve? Does the offer solve the immediate problem, or merely move the pressure to the next pay cycle? Those questions are more valuable than simply finding the fastest possible application route.
A useful workflow for an emergency expense
Imagine that a car repair appears just before rent is due. I would first open the app and identify the amount needed, resisting the temptation to request more simply because a larger figure appears available. Next, I would carefully read every repayment detail, fee, due date, and authorization request shown during the process. I would then compare the total cost with alternatives such as asking the repair shop about a payment arrangement, contacting a credit union, or using an existing emergency fund.
That comparison step is where the app can be genuinely helpful, even though it is not itself a complete financial counseling service. It gives the borrowing decision a clear place to begin, while the responsibility for checking affordability remains with me. If the repayment would leave me short for essentials, I would stop rather than treat the app’s convenience as evidence that the loan is suitable.
A less obvious benefit of this workflow is that it encourages a distinction between urgency and affordability. Those are not the same thing. A fast application can address the first problem while making the second worse. I recommend writing down the expected repayment date before submitting anything. If the date depends on uncertain overtime, a delayed paycheck, or another loan, that is a warning sign that the advance may not be a sensible fit.
Where it compares favorably with familiar alternatives
Compared with a traditional bank’s broader mobile app, this service is more specialized. A bank application may be better for checking balances, moving money, managing an established line of credit, or reviewing long-term finances. It can also feel slower or more complicated when the user is only investigating a cash advance. This app’s advantage is concentration: it does not ask me to navigate a full banking ecosystem before reaching the relevant subject.
Compared with a budgeting app, the difference is even clearer. Budgeting software helps prevent emergencies by showing where money goes, but it does not necessarily address an immediate shortfall. Cash Advance: Get 250 Fast is aimed at the moment when prevention has already failed or when an unexpected expense has arrived. I would not install it expecting spending analysis, savings coaching, or investment features.
Compared with asking friends or family for help, an app can feel more private and less emotionally difficult. That convenience has a trade-off: a personal arrangement may be more flexible or less expensive, while a formal advance can introduce fees and a rigid repayment obligation. Compared with a credit card, the right choice depends on the actual terms, available limit, and repayment plan. I would never assume that the app is automatically cheaper simply because the application looks easier.
The absence of subscription fees is another attractive part of the proposition. It means the app itself is not presented as a recurring membership expense. However, that should not be read as “borrowing costs nothing.” The relevant figure is the complete cost of the advance, including any charges connected with the transaction and the consequences of late repayment. I would focus on that total rather than on the free download.
Where the experience needs caution
The main weakness is not necessarily the interface; it is the risk created by the product category. Payday loans and cash advances can be useful in a tightly controlled emergency, but they can also create a cycle in which one short-term advance is used to cover the previous one. A polished mobile process can make that risk feel smaller than it really is. In my view, the app would be a poor choice for recurring expenses, ongoing debt, or a gap that appears every month.
Users should also keep their expectations realistic. A simple application process does not mean approval is guaranteed, and reaching a later stage does not automatically mean the final terms will suit the borrower. I would read each screen slowly, capture important details for my records, and avoid entering information while distracted. If the wording is unclear, I would pause until I understood the obligation rather than relying on the speed implied by the app’s name.
Privacy deserves the same attention as cost. Any finance application may require personal and financial information to evaluate or process a request. Before proceeding, I would inspect the permissions and disclosures presented on the device and in the relevant store materials. I would also make sure I am using the official application from the named developer, KOMPANIIA LORENS PP, rather than an imitation with a similar title.
Another limitation is that focused borrowing tools are not designed to replace human advice. If I were already behind on several bills, facing unstable income, or considering one advance to repay another, I would look for help from a nonprofit credit counselor, a trusted financial professional, or a local assistance service instead. The app may show a route to short-term cash, but it cannot solve the underlying income-and-expense imbalance.
Questions I would answer before applying
The first question is whether the expense is truly urgent. If a purchase can wait a week, postponing it is usually safer than taking on a new obligation. The second is whether repayment can be made from money that is already expected, not money that I merely hope will arrive. The third is whether paying back the advance would affect rent, utilities, food, transportation, or other essentials.
I would also ask what happens if repayment is late. The answer should be clear before submitting an application, not discovered after the due date passes. I would look for the total repayment amount, timing, possible fees, and any consequences explained in the process. If those details are difficult to locate or understand, that uncertainty alone would make me step away.
Finally, I would compare at least one alternative. A payment extension, employer advance, credit union product, existing overdraft arrangement, or help from someone I trust may be less costly or more flexible. The app is most useful when it is one option in a comparison, not the only option considered under pressure.
Who will get the most from it
This app is best suited to an adult who understands short-term borrowing, has a specific one-time need, and can identify a dependable repayment source. The Everyone rating describes the content classification, but it should not be taken as a recommendation for children or as evidence that borrowing is appropriate for every user. Financial responsibility still depends on age, income, local rules, and personal circumstances.
It may also suit someone who prefers handling an initial inquiry privately on a phone rather than visiting a branch. The free installation removes a barrier to exploring the process, and the focused design can be easier to navigate than a general banking platform. I would recommend it to a careful borrower who is willing to read the terms and compare the result with alternatives.
I would skip it if I needed a long-term solution, wanted detailed budgeting tools, or was already struggling with several debts. Someone with predictable savings goals would be better served by a budgeting or savings application. Someone seeking a larger, structured loan may be better off comparing established banks or credit unions. Someone who cannot explain how the advance will be repaid should not use speed as a reason to proceed.
The app’s popularity, reflected in its substantial install base and large number of ratings, makes it easier to see why people are curious about it. Even so, popularity does not remove the need for personal due diligence. I would judge it by the clarity of the terms offered to me, not by the average rating alone.
My final verdict on Cash Advance: Get 250 Fast
After looking at the app as both a product and a borrowing decision, I see a useful but limited tool. Its strongest quality is a focused, accessible route into the cash advance process, without the distraction of a full financial dashboard or a subscription charge for the app itself. That can matter when someone is trying to understand an emergency option quickly.
Its greatest weakness is inseparable from its purpose: short-term borrowing can become expensive or stressful when used repeatedly. The app’s clean approach should make the process easier to inspect, not easier to ignore. I would use it only after calculating repayment, checking every condition, and comparing alternatives.
My recommendation is therefore cautious but positive for the right person. If you have a one-off emergency, a dependable repayment date, and the discipline to stop when the terms do not work, this finance app is worth examining. If the problem is ongoing or the repayment plan is uncertain, choose a budgeting, counseling, banking, or community-support option instead. The most important feature is not speed; it is knowing exactly what the advance will cost before you accept it.
For me, that makes Cash Advance: Get 250 Fast a reasonable starting point rather than a universal solution. It earns consideration because it stays focused and approachable, but it deserves the same careful scrutiny as any other financial commitment. Used selectively, it can help organize an urgent decision. Used casually, it could make a temporary shortage harder to escape.
Pros
- Quick application process with a straightforward interface
- May help cover unexpected short-term expenses
- Clear repayment details are shown before accepting an offer
- Available from a mobile device without visiting a branch
- Useful for users comparing potential advance options
Cons
- Approval and advance amounts depend on eligibility requirements
- Fees or borrowing costs may make repayment more expensive
- Repayment deadlines can arrive quickly after receiving funds
- Not available to all users or in every state or region
- Requires sharing personal and financial information for review
- Category
- Finance
- Version
- 1.2.2











