Borrow Cash Instantly WeDollar
- 1.02K
- 4.7
- Installs
- 100.00K
- Price
- Free
Screenshots
Analysis by Reviewed
Borrowing money through a phone is one of those decisions that feels simple until the repayment details matter. I approached Borrow Cash Instantly WeDollar as a practical finance app rather than treating instant access as an automatic benefit. Its purpose is clear: it is designed around borrowing money and cash-advance requests, so the real question is not whether it can make a request feel quick, but whether that kind of short-term borrowing suits your situation.
The app is free to install, aimed at Everyone, and comes from Voronkov Moner App. It has built a noticeable audience, with a 4.7 average from around 30 thousand ratings and over 100 thousand installs. Those figures suggest that many people find the basic idea useful, but they should not replace a careful look at the repayment commitment. In my experience, a borrowing app deserves a different kind of review from a budgeting tool: convenience matters, but clarity and self-control matter more.
How I Decide Whether WeDollar Fits
My first test is purpose. WeDollar is not something I would open casually to browse financial information. The app is centered on borrowing, with instant cash-advance options presented as its main use. That makes it relevant when a person has a short-lived cash gap and a clear plan for covering the obligation. It is much less suitable when the request is being used to support an expense that will continue month after month.
The second test is urgency. A quick request can be helpful when timing is genuinely important, but urgency can also encourage rushed decisions. Before using the app, I would write down the amount needed, the date when repayment should be possible, and the money that must remain available for rent, food, transport, and existing bills. If those basics do not fit on paper, an instant option is unlikely to solve the underlying problem.
The third test is comparison. I would compare this kind of cash advance with the alternatives already available to me: delaying a nonessential purchase, asking a trusted person for help, using an existing bank facility, or choosing a conventional financial product with a longer repayment structure. I would not assume that a faster application is automatically cheaper or safer. The right choice depends on the total obligation and how predictable my income is.
There is also a practical privacy and account-safety test. I would install the app only from the official Android or iOS source, check that the developer name matches Voronkov Moner App, and read every permission and agreement screen before continuing. I would never share a verification code with another person claiming to “speed up” the process. These habits are especially important with any service involving identity, banking details, or borrowing.
The Everyday Scenario Where It Makes Sense
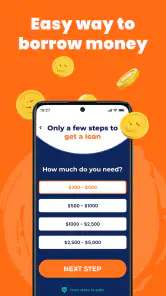
Imagine a necessary bill arriving just before a regular paycheck, while the amount needed is limited and the next income date is reliable. In that situation, an app focused on an instant cash advance may be more convenient than visiting a branch or starting a lengthy application elsewhere. I can see the appeal: one place to begin the request, less physical paperwork, and a process designed for a time-sensitive need.
Even in that scenario, I would treat the app as a bridge, not extra income. I would request only the amount required, avoid rounding upward for optional spending, and record the repayment date immediately. A useful personal rule is to leave enough room in the next budget for ordinary expenses after repayment. If paying back the advance would create another shortfall, the convenience has only moved the problem forward.
That workflow is one of the less obvious strengths of a borrowing app: it can make a small, defined request easier to separate from general spending. The weakness is equally important. A smooth mobile experience can make borrowing feel like a normal purchase, even though the financial consequences are different. I would pause after entering the amount and review the final terms with the same care I would use for a paper agreement.
What the App Does Well for a Focused User
WeDollar’s strongest point is its narrow purpose. Someone looking specifically for a way to request borrowed money does not have to search through a broad collection of unrelated finance tools. The store summary emphasizes instant cash advances, and that focus makes the app easier to understand at a glance than a general-purpose money-management application.
I also value the fact that it is free to install. That removes an initial download charge, which is appropriate for an app people may want to examine before deciding whether to proceed. Still, free installation should not be confused with free borrowing. I would judge the service by the complete financial commitment shown during the request, not by the app’s download price.
The Everyone content rating makes the app broadly accessible from an age-classification perspective, but that does not mean every borrowing decision is appropriate for every user. Financial responsibility still depends on income, existing obligations, and the ability to repay. I would explain that distinction to a younger or inexperienced user before allowing them to make a request.
The current version is 2.0.2, and the app supports Android 7.0 or later. That makes it relevant to people using older Android phones rather than only recent devices. I would still keep the operating system updated where possible and install updates through the normal store process. Compatibility is useful, but security and device maintenance remain part of the decision.
Small Habits That Make the Experience Safer
My first practical tip is to prepare before opening the request screen. I would have my identification details, income information, and repayment plan ready, while avoiding guesses or inflated figures. Accurate information reduces the chance of making a rushed mistake and gives me a better basis for deciding whether the requested amount is realistic.
My second tip is to separate approval from affordability. Even if an application moves forward, I would not treat that as proof that repayment will be comfortable. I would calculate the effect on the next pay cycle and check whether an existing bill could collide with the repayment date. This is a useful mental separation because borrowing eligibility and personal affordability are not the same thing.
My third tip is to save the important details in a private place after completing a request. I would note the amount, due date, and any applicable charges exactly as shown in the agreement. I would not rely on memory or on finding the same screen later. A calendar reminder is also worthwhile, particularly when the advance is being used during a stressful week.
A fourth habit is to avoid repeated emergency borrowing. If I needed another advance before the first one was comfortably resolved, I would stop and reassess the budget instead of stacking requests. That pattern can turn a temporary gap into a cycle. WeDollar may be useful for a defined event, but no instant-cash tool can replace a sustainable income-and-expense plan.
Where Other Choices May Be Better
WeDollar is not automatically the best option for every type of financial need. If I need money for a large purchase, a conventional loan or an established bank product may offer a more suitable structure, depending on the terms available to me. If I need help organizing spending, a budgeting app would address the real problem more directly. A cash advance can provide liquidity, but it does not teach me where the budget is leaking.
If the expense is optional, waiting may be the strongest alternative. Delaying a purchase costs no borrowing charge and removes the pressure of a repayment date. For a genuine emergency, a trusted family member or friend may also be an option, although that choice can affect personal relationships and should be handled honestly rather than casually.
People with irregular income should be especially cautious. A repayment plan that works after a predictable paycheck may become uncomfortable when freelance work, seasonal pay, or commissions arrive late. In that case, I would favor an option whose schedule matches the income pattern, even if the application takes longer. Speed is less valuable when the repayment date is uncertain.
There is also a difference between a cash-advance service and a credit-building or long-term financial product. Someone trying to establish a broader financial history may need to investigate products designed for that purpose instead of choosing a short-term advance simply because it is convenient. I would not use WeDollar as a substitute for a savings account, emergency fund, or debt-management plan.
For users who dislike entering financial information into a mobile service, the better alternative may be a provider they already know and trust. Familiarity does not guarantee good terms, but it can make it easier to understand account support and existing records. My own preference would be to compare the final obligation in writing rather than choosing based only on a polished request flow or the promise of speed.
The Cost of Switching Between Options
Switching from a traditional route to WeDollar may reduce the time spent applying, but it can also change how I track the obligation. A bank account may already show regular transactions and reminders, while a separate borrowing app requires me to create my own system. That is a small administrative cost, but missing a due date can make it significant.
Switching in the other direction can feel slower. A conventional provider may require more steps, more documentation, or a longer wait before a decision. The trade-off is that a slower process may encourage a more deliberate review of the amount and repayment schedule. I would accept that extra friction when the need is not truly urgent or when the amount is too important for a quick decision.
There is a behavioral cost as well. Once an instant borrowing app is installed, it becomes an easy option the next time money feels tight. I would therefore keep it for a clearly defined purpose, disable unnecessary notifications if the phone offers that control, and remove it when I no longer need access. That is not a criticism of this particular app; it is a sensible boundary for any tool that makes borrowing readily available.
Before switching, I would also make sure that any existing obligation is settled or properly documented. I would not assume that installing another finance app transfers records, reminders, or repayment responsibilities. Keeping a simple private record avoids confusion when more than one financial service is involved.
Who Should Use It and Who Should Skip It
I would recommend considering WeDollar to someone facing a limited, time-sensitive expense who has a dependable repayment plan and is willing to read the agreement carefully. The app’s focused borrowing purpose, free installation, broad age classification, and support for older Android devices make it approachable for that narrow use case. Its strong user response, including a 4.7 average from around 30 thousand ratings, also indicates that the concept has worked for many users.
I would advise skipping it if the money is needed for recurring bills, if repayment depends on an uncertain future payment, or if another advance is already being used to cover an earlier one. I would also choose a different category of app when the real goal is spending control, saving, investing, or long-term debt management. Those needs require tools built around planning rather than immediate borrowing.
My final recommendation is cautious but positive: WeDollar is worth examining when the need is short-term, specific, and fully budgeted. I would not install it with the expectation that instant access solves financial stress. I would install it only after deciding the amount I can repay, reviewing the complete terms shown in the app, and comparing the result with slower alternatives. Used with that discipline, it can be a practical option; used impulsively, its greatest convenience can become its biggest weakness.
Pros
- Fast access to short-term borrowing options
- Simple application process with minimal paperwork
- Clear repayment information before accepting an offer
- Useful for comparing available loan offers
- Mobile-friendly interface and convenient account access
Cons
- Approval and loan availability may vary by location
- Interest rates and fees can be high for some borrowers
- A credit check may be required during the application
- Repayment periods may be relatively short
- Sharing personal and financial data raises privacy concerns
- Category
- Finance
- Version
- 2.0.2











