Piere: Budget, Plan, Save
- 188.00
- 4.5
- Installs
- 50.00K
- Price
- Free
Screenshots
Analysis by Reviewed
I approached Piere: Budget, Plan, Save as a practical finance app rather than a flashy money dashboard. Its central idea is simple: give your spending a structure, then make saving feel less dependent on willpower. That makes it interesting for anyone who wants a clearer routine around money without turning every purchase into a manual spreadsheet entry.
In my experience, the app is most useful when you already have a basic income pattern and a few goals in mind. It can help you think in terms of planned spending and automatic saving instead of checking your balance only after money has disappeared. It is free to install, with optional in-app purchases ranging from $1.99 to $79.99 per item, so the sensible approach is to explore the free experience first and decide whether the extra cost fits your needs.
How Piere feels in everyday use
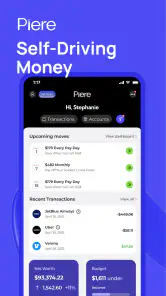
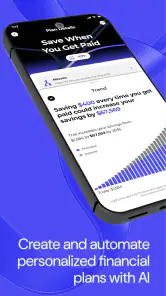
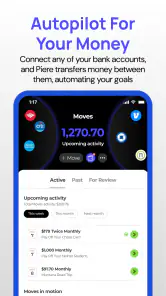
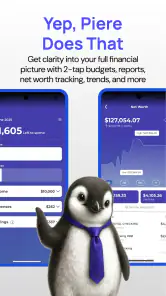
The strongest part of the concept is the connection between budgeting and saving. Many finance apps treat these as separate chores: one screen shows expenses, another shows goals, and the user has to connect the dots. Piere is designed around the idea that a budget should actively support a saving habit. That gives the app a more purposeful feel than a simple expense log.
I found this approach especially relevant for irregular everyday spending. A budget can look perfectly healthy at the start of the month, then slowly weaken through food orders, transport, subscriptions, and small purchases. A saving plan gives those decisions a destination. Instead of asking only, “Can I afford this?”, I would also ask, “Does this move me closer to the goal I set?”
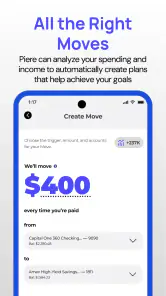
A realistic example is a person paid near the beginning of the month who wants to build an emergency cushion. With Piere, the useful routine is to set the main spending boundaries early, identify the amount intended for saving, and then check the plan before making flexible purchases. The app is not a substitute for discipline, but it can make the consequences of casual spending easier to see.
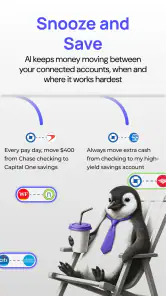
That distinction matters. Automation can remove repeated effort, but it does not make an unrealistic budget realistic. If your income changes often, or if essential bills vary significantly, you will still need to review the plan and adjust it. I would treat the automation as a helpful assistant, not as a financial autopilot that can safely be ignored.
A good fit for goal-oriented budgeting
Piere makes the most sense for people who have a specific reason to save: a buffer for unexpected costs, a planned purchase, a move, or simply the desire to stop ending each month with nothing left. A goal gives the budgeting process an emotional anchor, and that is where this app feels more motivating than a list of categories alone.
It can also suit someone who has tried a spreadsheet and found it too demanding. Spreadsheets offer impressive control, but they require consistent maintenance. A dedicated finance app is more convenient for quick checks and recurring habits. The trade-off is that you may have less freedom to design every detail exactly as you would in your own workbook.
I would be more cautious if you need advanced accounting, detailed business bookkeeping, complex shared finances, or highly customized reporting. Piere is positioned as a personal money-management tool, not a replacement for professional accounting software. Users who enjoy entering every transaction by hand may also prefer a manual tracker because it gives them a stronger sense of control.
What the current release tells me
The current version is 6.2.2, which suggests a product that has moved beyond an early first attempt and is being maintained as a usable finance service. I would not interpret a version number by itself as proof that every rough edge has disappeared, but it does make the app feel more established than a brand-new budgeting experiment.
Piere was released on Apr 8, 2024, and is developed by UniversTech. Its current public presence is also meaningful: it has passed 50K installs, with a 4.5 average from 473 ratings and 188 written reviews. Those figures do not tell me whether it will match my personal workflow, but they do indicate that the app has attracted a real user base and enough feedback to be worth investigating.
The age rating is Everyone, which fits the app’s general purpose. That does not mean every financial decision inside it is suitable for every user; it simply makes the product approachable for a broad audience. A teenager learning basic budgeting, a student managing limited income, and an adult organizing household spending may all use the same core idea, although their plans will need to be very different.
Changes and what they mean for existing users
For someone already using Piere, the arrival of version 6.2.2 is best viewed as a reason to update and reassess the day-to-day experience, rather than as a promise of a completely redesigned product. Current users should check whether their existing budget categories, saving routines, and personal habits still feel clear after updating. Finance apps are especially sensitive to small workflow changes because a minor change in where information appears can affect whether people review their plans regularly.
New users should start slowly. I would not build a complicated financial system on the first day. Begin with the few spending areas that genuinely affect your month, create one meaningful saving objective, and observe how the plan fits real life. This gives you a better test of the app than filling it with dozens of categories that you will stop maintaining after a week.
One non-obvious advantage of this gradual approach is that it exposes unrealistic assumptions early. If the plan repeatedly leaves too little for groceries or transport, that is not necessarily an app failure. It may show that the budget was based on an ideal month rather than your actual behavior. Piere is more useful when you let real spending teach you where the plan needs adjustment.
Another useful habit is to review the budget at a fixed point in your pay cycle, not only when you feel worried. A short review after income arrives can confirm what is available for essentials, flexible spending, and saving. A second check later can reveal whether an apparently harmless category is quietly consuming money intended for a goal.
Where it compares with familiar alternatives
Compared with a basic banking app, Piere has a more deliberate planning mindset. A banking app is excellent for seeing balances and transactions, but it often leaves the interpretation to you. Piere’s appeal is that it encourages a forward-looking conversation with your money: what should be available, what should be protected, and what should be saved?
Compared with a spreadsheet, the attraction is convenience. You do not have to build formulas or design a dashboard before you can begin thinking about a budget. The downside is flexibility. A spreadsheet can be shaped around unusual income, multiple currencies, detailed household rules, or a very personal classification system. If that level of customization is central to your method, a spreadsheet may remain the better tool.
Compared with a purely manual expense tracker, Piere aims to reduce the amount of repeated work involved in maintaining the plan. That can make it easier to stay consistent, but it also means you should not assume that every automated result deserves blind trust. I recommend checking important entries and confirming that the way the app presents your finances matches your own records before making major decisions.
Compared with an envelope-style budgeting method, Piere may feel less tangible. Physical or virtual envelopes give each amount a very concrete boundary, while an app can feel more abstract. On the other hand, a digital plan is easier to review when you are away from home and less cumbersome when your spending changes during the month.
Small workflows that improve the experience
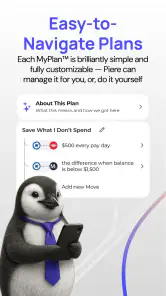
My first practical tip is to create a budget that reflects decisions you can actually make. Fixed bills deserve attention, but flexible categories are where the app can change behavior. If dining out, entertainment, or impulse shopping regularly affects your saving goal, those categories should be visible enough to guide a choice before the money is spent.
My second tip is to use one primary goal before creating several secondary goals. Too many targets can divide your attention and make progress feel invisible. A single priority gives the automated saving idea a clearer purpose. Once that routine feels stable, adding another goal becomes easier to evaluate.
My third tip is to treat the budget as a forecast rather than a judgment. If a month goes wrong, do not simply abandon the plan. Look at which assumption failed: income timing, an annual bill, a forgotten subscription, or an overly optimistic allowance for variable spending. This turns Piere into a learning tool instead of a monthly test that you can fail.
A fourth trade-off is worth mentioning for households. If two people share expenses, the app can be useful as a planning reference, but you should agree on who reviews the budget and how shared purchases are handled. A finance app cannot resolve disagreements about priorities. Without a shared routine, even a clear plan can become another source of confusion.
Limits I would consider before committing
The biggest limitation is that automation can create false confidence. A plan that runs quietly in the background may feel complete even when your categories are outdated. Life changes faster than a budget: rent changes, travel appears, medical costs arrive, and income can fluctuate. Anyone using Piere should keep a regular review habit, particularly before increasing an automatic saving amount.
The optional purchase model is another point to weigh. The app is free, but in-app items can cost from $1.99 to $79.99 each. That broad range makes it important to understand what is included before paying. I would avoid purchasing an upgrade simply because a feature sounds convenient; first decide whether it solves a problem you actually encounter in your weekly money routine.
Privacy and account security should also be part of your decision whenever a finance app becomes connected to sensitive financial information. I would use a strong device lock, keep the app updated, and avoid treating any finance application as a place to experiment casually. The convenience of a unified money view is valuable, but it should be balanced with careful account habits.
Users who need investment analysis, tax preparation, debt counseling, or formal financial advice should look elsewhere or use Piere only as one small part of a wider system. It can organize intentions and habits, but it should not be mistaken for a professional adviser. Likewise, someone who dislikes automated systems may feel more comfortable with a local spreadsheet or a simple notebook.
What I would watch as the app develops
For future use, I would pay attention to how smoothly Piere handles changing circumstances. The most important test is not whether a budget looks attractive on a calm day, but whether it remains understandable after an unexpected expense, a change in income, or a month with unusually high spending.
I would also watch the balance between simplicity and control. The app’s appeal depends on making budgeting less tiring. If new options make the experience more powerful without making the basic routine harder to understand, that would be a positive direction. If the product becomes crowded with settings that ordinary users must configure, it could lose the approachable quality that makes it appealing in the first place.
Existing users should watch their own behavior as much as the release notes. Are you checking the plan more often? Are saving decisions clearer? Do you notice overspending earlier? Those answers are more useful than a version update alone. A finance tool earns its place when it changes a repeatable habit, not merely when it displays attractive numbers.
For new users, the best trial is a modest one: install the free app, set up a realistic budget, choose one saving priority, and use it through an ordinary pay cycle. That will quickly show whether the planning style suits you. There is no benefit in forcing yourself into a system that makes money management feel more complicated than it was before.
My final view
I like Piere because it focuses on the relationship between planning and saving rather than treating budgeting as a passive record of past purchases. The product is approachable, the current version feels mature enough to deserve a fair test, and its public reception gives it credibility without removing the need for personal judgment.
Still, I would recommend it selectively. It is a strong candidate for someone who wants a guided personal budget and a clearer saving routine, especially if spreadsheets feel like too much work. It is less convincing for users who need professional financial tools, unusual accounting structures, or complete manual control.
My recommendation is to use Piere as a weekly money check-in, not as a set-and-forget machine. If you review the plan, question unrealistic assumptions, and keep the optional costs in mind, it can turn vague intentions into a more visible routine. That is a useful role for a free finance app, and in my experience it is where this particular product has the best chance of helping.
Pros
- Simple budgeting tools make it easy to track spending and set limits.
- Clear visual summaries help you understand where your money goes.
- Useful savings goals encourage consistent progress toward personal targets.
- Planning features can help organize upcoming bills and financial priorities.
- A focused design keeps essential money-management features easy to find.
Cons
- Some advanced features may require a paid subscription.
- Manual transaction entry can become time-consuming for frequent purchases.
- Limited bank support may affect automatic account synchronization.
- New users may need time to learn the app’s budgeting workflow.
- It may not offer enough customization for complex household finances.
- Category
- Finance
- Version
- 6.2.2











