

MyCard - Contactless Payment
- 120.00
- 4.0
- Installs
- 10.00K
- Price
- $17.99
Screenshots
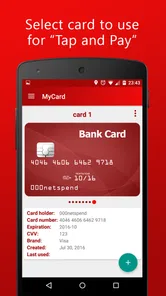
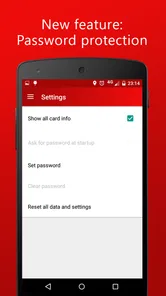
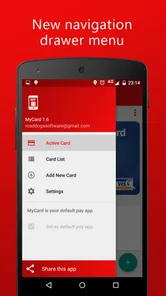
Analysis by Reviewed
I find the household question around MyCard - Contactless Payment more practical than it first sounds: when a phone can be used to pay, the owner, the account, and the person holding it all matter. I’d think of this finance app as a personal way to make a contactless payment, not as a shared family wallet. That distinction helps set expectations before a rushed checkout turns into a discussion about whose purchase it was.
Agree on who holds the phone
Imagine one adult is carrying groceries while another is asked to pay at the till. Handing over a phone may seem like the quickest solution, but I’d first check that the intended payment setup is the one being used and that the phone’s owner is comfortable with the other person making the purchase. Tap payments are designed to be quick; a brief check before passing the device around can avoid an accidental charge or an awkward moment.
For regular shared expenses, I’d decide in advance how the household handles them. One person can pay and the others can settle up using a method they already trust, or each adult can use their own payment method. MyCard can simplify the checkout step, but I would not treat the app itself as a way to divide bills, set spending limits for family members, or keep a shared household budget.
Keep the payment setup personal
Before making the app part of a household routine, I’d decide whose phone and payment setup it belongs to. If two adults take turns paying, keeping the app on one person’s device makes responsibility clearer; the other person can use their own card or payment method. That arrangement is not as convenient as passing one phone back and forth, but it avoids blurring who is authorizing a payment.
I’d also think about the situations when the phone is not available. A drained battery, a forgotten device, or a checkout that does not accept contactless payments can interrupt a phone-first habit. Keeping another way to pay nearby is sensible, especially if you are shopping on behalf of someone else. It does not take away from the convenience of tapping; it simply means you are not relying on one device for every purchase.
Paying by phone in everyday life
What I like about paying by phone is how it can make a familiar checkout feel less fiddly. When my wallet is buried in a bag and my phone is already in my hand, a contactless payment is a straightforward option for an everyday purchase. It is a small convenience rather than a reason to change every part of how I pay, and that is the most realistic way to judge MyCard.
What a quick checkout is good for
A useful test is a small, routine purchase in a shop where contactless payment is accepted. You can see whether the app fits your normal phone use without making an important or time-sensitive purchase your first attempt. If the process works for you, it may be handy for a coffee, groceries, or another ordinary checkout. I’d still keep a backup payment method available until I know the setup suits my routine.
More From Our News Desk

 Gmail
Gmail in a Busy Inbox: Who Benefits Most?
From first account to crowded workday, Gmail earns its place through dependable search and flexible sorting—but its best fit depends on how much inbox maintenance you can tolerate.

 Prime Video
Switching to Prime Video: What Changes in Your Viewing Routine
Prime Video can make a compelling second home for streaming, but switching means learning a different catalog, rental layer, and route from browsing to playback.

 Universal TV Remote Control
 Works Best as a Reliable Backup
A phone remote earns its place through quick setup and reliable habits. Here is how to get more from Universal TV Remote Control—and where its limits show.

 Weather - By Xiaomi
Weather by Xiaomi Review: Clear at a Glance, Less Clear Up Close
Xiaomi’s weather app makes everyday forecasts quick to scan, but its calm surface can leave useful details and recovery paths harder to find than they should be.

 X
X Under Pressure: Can It Recover When Posting Goes Wrong?
A resilience-focused review of X, examining setup, mistaken posts, interruptions, weak connections, and the gaps that matter when recovery needs to be dependable.

 Clash of Clans
 Is Won Between the Battles
Its raids are quick; its community is a long-term project of coordination, teaching, rivalry, and shared responsibility—with all the friction that entails.
Latest News



This phone-first approach is most appealing to someone who usually has their phone close at hand and wants another way to pay without reaching for a physical card. It is less compelling if your bank card already feels effortless, if you prefer cash, or if you need multiple household members to pay independently from separate accounts. In those cases, the familiar alternative may be simpler than introducing a new app.
Age and trust need separate decisions
The Everyone age rating describes the app’s content category; I would not read it as permission for a child to use an adult’s payment account. If a younger person borrows the phone, keep the account holder involved and be clear about whether the app may be opened or a payment made. A familiar interface does not remove the need for an adult to supervise access to their own payment method.
Among adults who share expenses, coordination can be just as important. Agreeing who pays for a grocery run and how the cost will be settled later is more reliable than assuming a contactless app will keep track of everyone’s contribution. If the actual need is expense sharing or household budgeting, I’d choose a tool intended for those tasks and use a payment app only for the checkout itself.
Simple use, with sensible expectations
For me, the best way to approach any phone payment setup is to separate convenience from control. A tap can reduce the little delays involved in finding a wallet, but it does not automatically make a phone suitable for lending or turn one person’s payment method into a shared account. That distinction matters most in homes where phones are passed around, children borrow devices, or several adults divide errands.
I would make the first try low stakes: use it for a modest purchase, keep another way to pay available, and notice whether the phone and checkout routine feel comfortable. If you are shopping for someone else, confirm whose payment method is being used before you tap. Those small habits are more useful than assuming that a fast payment flow will resolve questions about permission or reimbursement.
A shared phone needs clear boundaries
For a household, the practical question is not just whether a phone can make a quick payment, but whose payment method is being used and who is holding the device. I’d treat MyCard as a personal payment tool, not as a shared family wallet: before anyone else uses the phone, agree on whether they may open the app or make a purchase. That simple conversation can prevent an awkward checkout and confusion over whose spending is involved.
A realistic example is a parent handing over a phone while carrying groceries. If another person is asked to pay, I would first make sure the right account is active and that the device owner is comfortable with the transaction. Contactless speed is useful in a busy shop, but it also makes a quick check worthwhile. For regular household spending, a shared physical card or another arrangement designed around multiple users may be easier to manage.
Setting it up without mixing accounts
Because this is a finance app, I’d decide whose phone and payment setup it belongs to before making it part of a household routine. If two adults take turns paying, keeping the app tied to one person’s device can make responsibility clearer; the other person can carry their own card or use their own payment method. That may feel less seamless than sharing one phone, but it avoids treating a personal payment setup as a household account.
It also helps to think through the moment a phone is unavailable. A drained battery, a forgotten device, or a checkout where contactless payment is not accepted can interrupt a phone-first routine. I’d keep a backup card or another way to pay, especially when running errands for someone else. This is not a reason to avoid tap payments; it is a sensible boundary for any digital payment habit.
User-Friendly Interface
The user interface is clean and intuitive, making it super easy for anyone to navigate. Whether you’re a tech-savvy millennial or someone who’s not as confident with technology, you’ll find it a breeze to use. The app layout is straightforward, with everything you need just a tap away. And the best part? It doesn’t bombard you with unnecessary ads or distractions.
Security at Its Best
Now, I know what you’re thinking: "Is it safe?" Absolutely! MyCard ensures top-notch security with its encryption protocols. Your details are as safe as a secret recipe locked in a vault. Plus, with biometric authentication options like fingerprint or face recognition, you can be assured that only you can access your account. It’s like having a personal security guard for your finances.
Trust, age, and everyday coordination
The app is rated Everyone, but that age label is not the same thing as permission for a child to spend from an adult’s payment account. I would not hand over a phone with payment access just because a younger family member can use the interface. Keep the account holder involved, and make expectations explicit: who may carry the phone, whether anyone else may open the payment app, and who checks that a purchase is appropriate.
For a couple or housemates, the useful coordination is often simple: decide who pays for a shared grocery run, then settle up through whatever method you already trust. MyCard can make the moment of paying quicker, but it should not be mistaken for a tool that assigns household expenses or separates personal budgets. If tracking who owes what is the main problem, a budgeting or expense-sharing option is a better fit than relying on a contactless payment app alone.
Compatible and Convenient
One of the things I love about MyCard - Contactless Payment is its compatibility with multiple devices and platforms. Whether you’re using an Android or iOS device, this app has got you covered. It integrates smoothly with other apps and services, making it the ultimate companion for your digital lifestyle.
And let's not forget about the convenience factor. Imagine being able to store all your loyalty cards, coupons, and tickets in one place. It’s like having a digital wallet that’s always organized and readily available whenever you need it. Talk about a lifesaver!
Where it sits among payment options
Compared with carrying a bank card, a phone-based tap can be handy when your wallet is at home and your phone is already in hand. Compared with cash, it avoids counting notes and coins at the till. But it depends on having a usable phone and a checkout that accepts contactless payments, so I would not make it the only option in my pocket. If several people need independent access, separate cards or accounts are usually clearer than passing around one device.
MyCard is a finance app from Road Dogs. It has a 4.0 average from around 285 ratings, with over 10,000 installs. It costs $17.99, so I’d weigh that upfront price against how often I expect to use it and whether my existing bank or wallet already covers the same everyday need. The app was released in March 2016, and its current version is 1.21, with Android 5.0 as the minimum operating system. Those details make compatibility worth checking before relying on it for regular payments.
The Future of Payments
If you’re still on the fence about going digital with your payments, let me tell you, MyCard is the future. It’s efficient, secure, and incredibly convenient. Whether you’re paying for your morning coffee or buying groceries, it simplifies the entire process. Plus, it’s constantly updated with new features, ensuring you always have the best experience.
My practical advice is to try it first in a low-pressure situation, such as a small shop purchase, while keeping another payment method available. That gives you a chance to see whether the setup suits your phone and routine before you depend on it for a larger grocery trip. If your main goal is fast personal checkout, that convenience may justify the cost; if you want shared balances, household controls, or a way to track everyone’s spending, I’d choose a service built specifically for those jobs instead.
In conclusion, if you’re looking to make your life easier and ditch the hassle of cash and cards, give MyCard - Contactless Payment a try. It’s more than just an app; it’s like having a personal assistant in your pocket. So go ahead, make the switch, and experience the future of payments today!
MyCard - Contactless Payment Frequently Asked Questions
What phones and operating systems can run MyCard?
MyCard is a Finance app with a minimum Android OS requirement of version 5.0. Before downloading, check that your device meets that requirement and has NFC, since the app is intended for contactless payments. Its age rating is Everyone, so it is suitable for a general audience. The app is available for $17.99.
What is MyCard - Contactless Payment?
MyCard - Contactless Payment is a mobile application designed to facilitate seamless and secure contactless payments through your smartphone. It allows users to link their credit or debit cards and use their device to make payments at contactless-enabled points of sale. The app is an NFC mobile payment option and offers a convenient alternative to carrying physical cards.
How do I set up MyCard on my device?
Setting up MyCard on your device is straightforward. First, download the app from the Google Play Store or Apple App Store. Once installed, open the app and create an account or log in if you already have one. Next, you'll need to add your credit or debit cards by following the in-app instructions. Ensure your device has NFC enabled to use the contactless feature.
Is MyCard - Contactless Payment secure to use?
Yes, MyCard - Contactless Payment prioritizes user security by implementing advanced encryption technologies and secure authentication processes. The app requires biometric verification or a secure PIN for transactions, ensuring that your payments are protected. Additionally, personal card information is not stored on the device, minimizing the risk of data breaches.
Can I use MyCard internationally?
MyCard - Contactless Payment can be used internationally, but its availability depends on the country and the acceptance of contactless payments by local merchants. Before traveling, ensure your cards are authorized for international transactions and check if your destination supports contactless payments. Currency conversion fees may apply, depending on your card issuer.
Pros
- Easy to set up and use for quick payments.
- Supports multiple cards for convenience.
- Secure with encryption and biometric login.
- Works offline for most transactions.
- No extra fees for international payments.
Cons
- Limited bank partnerships reduce usability.
- Occasional app crashes reported by users.
- Not compatible with all older phone models.
- Some users find the UI cluttered.
- Customer support response can be slow.











