Cash Advance Now - Bear Loan
- 117.00
- 4.7
- Installs
- 10.00K
- Price
- Free
Screenshots
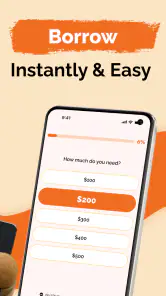
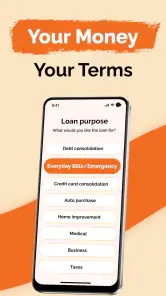
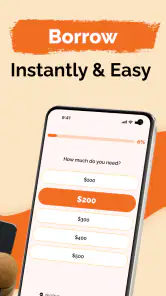
Analysis by Reviewed
When an unexpected bill lands between paydays, a cash-advance app can look like the quickest fix. I’d treat Cash Advance Now - Bear Loan as a possible short-term option to investigate, not as money I could count on before understanding the terms. Its finance focus is clear, but with borrowing, the useful question is not simply how fast an app feels: it is whether the amount, cost, timing, and repayment fit your actual situation.
Bear Loan is a free finance app from EPUTSTG QUALITY, described as a place to explore cash-advance options for online loans. It is rated for Everyone, and its 4.7 average across around 4,300 ratings suggests many users have responded positively. That can help when deciding whether it is worth a closer look, but a rating cannot tell you whether a particular offer is affordable or suitable for you.
Start with a careful borrowing workflow
Check the offer before planning around it
My first step would be to open the app and see what options are actually presented to me, rather than build a budget around the idea that an advance is guaranteed. An app that connects people with online loan options is not the same thing as a promise that every user will qualify for money. I would only treat an amount as available once the relevant terms and approval steps are clear.
Before moving forward, I’d look for the total amount I would need to repay, when repayment is due, and any fees or other costs shown for the offer. I would also check whether the repayment date falls before or after my next dependable income. If the app’s information leaves me unsure about any of those basics, I would pause and seek clarification instead of tapping through because I feel rushed.
A practical way to use Bear Loan is to begin with the smallest shortfall that solves the immediate problem. If a bill is slightly late, borrowing extra “just in case” can make repayment harder without adding much value. I’d write down the bill amount, the date it must be paid, and the money already available; then I’d compare the actual gap with the offer in front of me.
A realistic payday-week example
Imagine a utility bill is due several days before payday, and your account is short despite having enough income expected soon. I would first contact the provider to ask whether a due-date change or payment arrangement is possible. If that does not work, I’d use Bear Loan to examine whether a cash advance could bridge only that specific gap, then compare the repayment date with rent, groceries, transport, and other commitments already scheduled.
The key trade-off is that solving today’s bill can create a tighter week later. I would not count the same incoming pay twice—once for the advance repayment and again for normal expenses. A simple calendar note or budget entry can make the repayment visible before I accept anything. If the repayment would leave too little for essentials, the advance is not really fixing the problem; it is moving it.
More From Our News Desk
Clash of Clans Is Won Between the Battles
Android Auto Makes the Case for Quieter Car Software
MobiOffice: Transforming Mobile Productivity with Seamless Integration
EA SPORTS FC™ Mobile Soccer: Redefining Mobile Sports Gaming
How Microsoft OneDrive Became a Mobile Productivity Giant
How Google Translate Breaks Language Barriers Effortlessly
Build a repeatable check, not a borrowing habit
For an occasional decision, I’d use the same short checklist each time: what expense needs covering, whether it can be delayed or reduced, how much is genuinely missing, what the full repayment looks like, and what that repayment displaces. This makes it easier to compare one offer with another and prevents urgency from turning a quick glance into a commitment.
I would also keep a private note of the amount considered, the repayment date, and the final decision. That is not a special app feature; it is a personal habit that helps reveal whether a one-off bridge is becoming a recurring pattern. If I find myself reopening a borrowing app for ordinary weekly spending, I’d take that as a signal to review the budget or seek a different kind of support.
Settings and habits that deserve a second look
Review the terms and the information you share
Because this is a finance app, I would be more deliberate about setup than I might be with a casual utility. I’d read the permission prompts and privacy information shown during installation and use, and allow only what seems necessary for the service I intend to use. I would not assume that every prompt is harmless simply because an app is free, and I would avoid entering sensitive details until I understand why they are requested and how the process works.
Before submitting an application or request, I’d check that personal and financial information is accurate. A typo in a name, income detail, or contact field could create avoidable friction in a financial process. I’d also make sure I am using the intended app: the current version is 2.2.3, and the listed minimum operating-system requirement is version 7.0. Keeping the app current can be sensible, but it does not replace reading the offer itself.
Some people want alerts to keep a due date visible; others prefer to track commitments in a calendar they already trust. I would use whichever reminder method I reliably check, rather than assume the app has a particular notification control or repayment calendar. The useful setting is the one that helps me notice a deadline before it arrives, not one that makes borrowing feel automatic.
Separate convenience from affordability
A streamlined application can make it tempting to judge an offer by how easy it is to reach the next screen. I’d deliberately slow down at the point where costs and repayment terms appear. Convenience is a feature of the process, not evidence that the loan is a good deal. If another source—such as a bill extension, a trusted person, or a lower-cost borrowing option—solves the same problem with less pressure, I would compare that before proceeding.
That comparison matters especially if the shortfall is predictable. For a recurring expense, a small emergency fund or a conversation with the service provider may be more sustainable than repeated advances. Bear Loan may be useful to explore in a pinch, but it should not become the default line in a monthly budget unless the full repayment cycle genuinely works for you.
Faster decisions without rushing the choice
Use a two-pass review
When time is tight, I find a two-pass approach more reliable than trying to evaluate everything at once. On the first pass, I’d confirm that the app’s offer addresses the actual expense and that I understand the repayment date and total owed. On the second, I’d compare that repayment with the money already committed to essentials. If either pass raises a question, I would stop and resolve it instead of treating speed as the priority.
This pattern is useful because it separates eligibility from suitability. An offer might be available and still be a poor choice for the week ahead. Likewise, an attractive amount is not necessarily the right amount. I’d focus on the cost of solving this particular problem, not on the maximum I might be able to request.
Keep a comparison note for alternatives
Compared with a bank overdraft, a credit card, or asking a bill provider for extra time, an online cash-advance route may feel more direct. But those alternatives can differ substantially in cost, timing, and consequences, so I would compare the terms I can actually obtain rather than rely on broad assumptions. A provider extension could be better when it avoids borrowing; an established credit option could be better if its cost and repayment structure are clearer. If neither alternative is available, the app can still be worth examining—but only on its own terms.
A simple note with three lines—amount needed, total repayment, and repayment date—makes that comparison less fuzzy. I’d include any alternative’s cost in the same format. This is a small workflow improvement, but it prevents an app’s polished screens or familiar language from becoming the only frame of reference.
Know when to leave the process
I would back out if the offer is unclear, if the repayment date conflicts with essential bills, or if I am considering borrowing to repay another short-term loan. I would also avoid treating a positive rating as a substitute for reading the terms. Bear Loan has a 4.7 average and more than 10,000 installs, but neither figure can establish what an individual offer will cost or whether an individual application will be approved.
There are also people for whom this kind of app is simply the wrong starting point. If you need a long repayment period, predictable instalments, or advice about persistent debt, I’d look for a regulated lender or a qualified debt-support service that can address those needs directly. A cash-advance option is most defensible as a limited bridge for a specific, short-lived gap—not as a solution to income that repeatedly falls short of expenses.
Where the app fits—and where it does not
A useful option to inspect, not a financial plan
Bear Loan is aimed at people exploring online loan and cash-advance options, and the app is free to install. That makes it reasonable to consider when you want to review a possible short-term route from your phone. Its Everyone content rating also indicates that the app is not restricted to an older audience, though borrowing decisions still call for adult care and a clear understanding of the obligations involved.
Its strongest potential value is convenience: it gives a user a place to start examining an advance option without first visiting a physical branch. The limitation is just as important. App access does not make borrowing automatically affordable, and the existence of a route to an offer does not tell you whether its terms beat the alternatives available to you. I would judge it on the specific offer presented, not on the general promise of quick access.
My verdict after weighing the trade-offs
With 117 reviews alongside its wider user ratings, the app has some visible feedback, but I would still read recent comments for clues about people’s experiences and then verify all financial details in the app itself. It was released on May 9, 2026, so I would be especially careful not to confuse early impressions or popularity with a long record of dependable outcomes. What matters most is whether the current terms are understandable and manageable for your circumstances.
I’d recommend Bear Loan to someone who has a defined, short-term cash gap, wants to inspect an online advance option, and is willing to compare the repayment against their real budget before proceeding. I would skip it if I needed ongoing support, could not identify a credible repayment source, or felt pushed to accept an unclear offer. Used with a deliberate checklist and a firm limit, it may be worth exploring; used as a shortcut around a deeper budget problem, it is unlikely to help for long.
Cash Advance Now - Bear Loan Frequently Asked Questions
What is Cash Advance Now - Bear Loan?
Cash Advance Now - Bear Loan appears to be a financial app intended to help users explore cash-advance or loan options. The exact services, eligibility rules, and application process can vary by location and may change over time. Before sharing personal information, check the app’s current description and disclosures to confirm which company provides the service, whether it connects you with lenders, and what costs or obligations may apply.
Who may be eligible to apply for a loan through the app?
Eligibility depends on the provider’s current requirements and the laws where you live. Applicants may be asked for details such as age, residency, identity, income, employment, and an active bank account, but these conditions should not be assumed until confirmed in the app’s official terms. Meeting basic criteria does not guarantee approval, and any application should be completed only with information you can verify as accurate.
What fees, interest, or repayment terms should I check before applying?
Review the full cost of borrowing before accepting an offer, including the annual percentage rate (APR), interest, origination or service charges, repayment dates, and any late-payment or returned-payment fees. Confirm the total amount you must repay and whether payments are automatic. Loan costs and terms can differ between providers, so rely on the written offer and disclosures rather than assuming that an advertised advance is free or inexpensive.
Is Cash Advance Now - Bear Loan safe to use, and what information might it request?
A financial application may request sensitive information to verify your identity, assess an application, or process payments. Before submitting anything, confirm the developer and service provider, read the privacy policy and permissions, and check how data may be collected, shared, stored, or deleted. Download the app only from an official store, use a secure device, and avoid entering banking credentials if the request or destination seems unusual.
Will applying affect my credit score, and how quickly could I receive funds?
Credit-check practices and funding times depend on the lender or service provider, so neither an approval nor same-day funding should be assumed. Ask whether an eligibility check uses a soft or hard credit inquiry, and read the offer’s disclosure before proceeding. If approved, the time for money to arrive can depend on verification, the lender’s processing schedule, your bank, weekends, and holidays.
Pros
- Simple application process for users seeking a short-term cash advance.
- May offer a convenient alternative to visiting a lender in person.
- Loan details can help applicants compare repayment obligations before accepting.
- Useful for covering unexpected expenses when other options are unavailable.
- Applying through a mobile device can save time and paperwork.
Cons
- Approval and loan terms may depend on your location and credit profile.
- Fees and interest can make borrowing expensive if repayment is delayed.
- A cash advance is not a long-term solution for recurring money problems.
- Late or missed payments may lead to additional charges or credit consequences.
- Review the lender’s privacy policy before sharing sensitive financial details.
- Category
- Finance
- Version
- 2.2.3