SoLo Funds: Lend & Borrow
- 5.63K
- 4.6
- Installs
- 500.00K
- Price
- Free
Screenshots
Analysis by Reviewed
When I weigh a short-term money option, I start with a practical question: do I need access to a peer-to-peer lending community, or would a more predictable route suit me better? SoLo Funds: Lend & Borrow is built around people requesting and choosing loans rather than a conventional bank-style process. That makes it worth considering when timing is tight, but it also means I would treat every request as a decision to review carefully, not as guaranteed cash or guaranteed earnings.
Who benefits most from its person-to-person approach
I see the clearest fit for someone facing a specific, temporary expense who has a credible plan for repayment and wants to explore an alternative to borrowing from friends or using a conventional lender. On the other side, it may interest a lender who has money they can afford to leave unavailable and is comfortable assessing individual requests. In either role, I would avoid using money needed for rent, bills, or other near-term commitments: peer-to-peer lending involves uncertainty, and a possible return should never be treated like dependable income.
Picture a car repair landing just before payday. A borrower could use the app to present a request and repayment plan, then see whether a lender chooses it. That can feel more personal than applying through a traditional institution, but it is not a promise that the request will be funded in time. If the repair is urgent and the car is essential for work, I would compare other realistic options at the same time rather than relying on one request to solve the problem.
How I would judge a request before acting
The app’s community structure is useful, but it does not remove the need for judgment. As a borrower, I would ask myself whether the repayment date matches my actual cash flow, including other bills due around then. I would request only what the expense calls for and read the terms closely before accepting. A flexible arrangement is helpful only if the commitment remains manageable after the immediate problem has passed.
As a lender, I would treat the SoLo Score as one input rather than a guarantee. Repayment history and community endorsements can inform a decision, yet no score can make a personal loan risk-free. I would review the request, decide in advance what amount I can afford to have tied up, and avoid spreading myself thin by choosing several requests simply because they look appealing. The practical trade-off is clear: more personal choice comes with more responsibility for evaluating risk.
What is SoLo Funds All About?
SoLo Funds: Lend & Borrow is an innovative peer-to-peer lending platform designed to connect people who need a short-term loan with those willing to lend a little extra cash. The beauty of this app lies in its simplicity and accessibility. Whether you're a borrower looking for some quick cash to cover an unexpected expense or a lender aiming to earn a little return on your surplus funds, SoLo has got you covered.
Getting Started with SoLo Funds
Signing up for SoLo Funds is a breeze. Just download the app on your Android or iOS device, and you're ready to roll. The app's user-friendly interface makes the process of signing up and navigating through different options incredibly easy. I must say, the registration process was straightforward, and I was impressed by the app's clean design.
More From Our News Desk

 Bolt: Request a Ride
Bolt and the Shift from One-Tap Rides to More Legible Trips
Bolt shows how ride-hailing is shifting from a one-tap taxi request toward a more legible, choice-driven trip, while leaving the hardest questions of price and reliability unresolved.

 Farm Land - Farming life game
Farm Land Review: A Small Island Farm with a Satisfying Loop
A bright, breezy island farm turns a few quick chores into a satisfying cycle of planting, harvesting, expanding, and deciding what to build next.

 Android Auto
’s Community Takes Shape in the Passenger Seat
Its most valuable network is not a public feed but a shared set of routes, voice habits, app integrations, and advice that make driving less isolating—and sometimes more complicated.

 My Talking Angela
 Makes the Virtual Pet Feel Personal
A polished pet-raising game built on small rituals, playful customization, and a character who gives everyday screen time a surprisingly personal rhythm.

 Google Translate
 Review: A Pocket Tool for the Small Frictions of Travel
From menus and signs to quick conversations, Google Translate earns its place by cutting the little delays that make unfamiliar language feel like a barrier.

 Shazam: Find Music & Concerts
Shazam’s Best Trick Is Turning a Song Into a Night Out
A few seconds of recognition can settle an argument, rescue a half-remembered chorus, and point toward a live show. Shazam’s real trick is what happens after the match.
Latest News



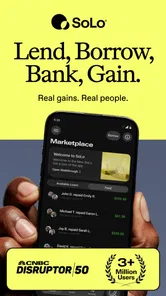
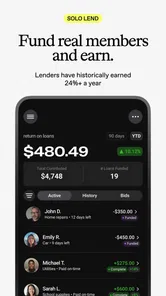
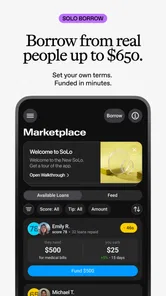
Once you're in, you'll notice that the app offers a seamless experience. As a borrower, you can create a loan request detailing how much you need and when you can repay it. Lenders, on the other hand, can browse through these requests and choose the ones that align with their lending criteria. It's like a match-making service for money!
Features that Stand Out
One aspect that makes SoLo Funds particularly appealing is its community-driven approach. Borrowers can set their own terms, and lenders can choose requests that suit their preferences. Plus, the app encourages transparency and communication between both parties, fostering a sense of trust and reliability.
Another noteworthy feature is the "SoLo Score," which helps lenders assess the risk associated with a borrower. This score is calculated based on various factors, including repayment history and community endorsements. It's a nifty tool that adds an extra layer of security for lenders.
Making the peer-to-peer trade-off clear
Compared with the usual alternatives, this app sits between asking someone you know for help and pursuing a more formal borrowing route. Its advantage is that borrowers can present terms to potential lenders, while lenders can choose requests instead of accepting a single fixed offer. Its disadvantage is the same feature viewed from the other side: neither a suitable match nor a particular outcome is something I would count on in advance. If certainty and a clearly defined repayment schedule matter more than flexibility, I would compare formal options before committing.
For a borrower, a useful habit is to draft the repayment plan before opening the request screen. Check when income arrives, list the bills that must come first, and make sure repayment still works if an ordinary expense appears. For a lender, I would make a personal rule about the amount I am willing to risk and stick to it. These small checks turn the app’s flexibility into a more deliberate choice rather than a spur-of-the-moment response.
Everyday use and sensible limits
One question people often have is whether this is better for an emergency or for regular borrowing. I would reserve it for a defined, short-term need, not build recurring spending around it. A request may be visible to lenders, but visibility is not the same as approval, so anyone facing a deadline should keep a backup plan. Likewise, lending is not a substitute for savings or a predictable investment: only consider it with funds that can remain unavailable and that you can afford to put at risk.
The app is free to download, and it is a finance app from Solo Funds. It has an Everyone age rating, a 4.2 average from around 21,000 ratings, and more than 500,000 installs. Those figures suggest that many people have tried it, but they do not tell me whether a particular loan request is a good fit. I would still read each screen and each proposed term carefully before making a decision.
Small choices that make the workflow safer
I would approach a request as a short planning exercise, not something to fill in while stressed. Write down the expense, the amount that would actually resolve it, and the date the repayment can realistically come from. Then test that date against known bills and ordinary spending. This helps prevent a common trap with flexible borrowing: solving today’s problem by creating a second shortfall later.
If I were lending, I would read requests when I had time to compare them rather than treating the app like a place to park spare cash automatically. The option to choose individual requests is meaningful only if I use it thoughtfully. I would decide my limit before browsing, consider whether I can tolerate delayed repayment, and avoid assuming that a score or an endorsement predicts what will happen in every case. That restraint matters more than trying to select the most appealing-looking request.
Another practical consideration is the difference between needing money and needing certainty. A peer-to-peer request may be worth exploring when I can wait for a possible match and have another plan if it does not happen. If a bill has a firm deadline, I would not treat the app as the sole solution. In that situation, contacting the biller, checking a formal borrowing option, or asking a trusted person with clear repayment terms may be more useful, depending on what is available to me.
When another route makes more sense
I would skip this approach if I need guaranteed funding by a particular hour, cannot confidently name a realistic repayment date, or would be lending money I need back soon. Someone who prefers a fixed process and less individual decision-making may be more comfortable comparing a bank or credit-union option, while a person with a trusted support network might first discuss a direct arrangement with clear written terms. Those alternatives have their own trade-offs; the key is to compare timing, obligations, and what happens if repayment becomes difficult rather than choosing by convenience alone.
Switching from a familiar borrowing habit also takes a little thought. Before creating a request, gather the amount you need, the reason for it, and a repayment plan you can actually keep. Before lending, set boundaries first, then assess requests within them. The app’s current version is 2.9.11 and it requires Android 8.0 or later, details worth checking against your device before you install it. I would also make sure I understand the terms shown in the app rather than assume that a simple interface means a simple financial commitment.
For anyone moving from a conventional lender, the biggest adjustment is that the decision is less like accepting a standard offer and more like presenting or judging a person-to-person request. That can suit someone who values choice, but it also asks more of both sides. Borrowers should be prepared for a request not to attract a lender; lenders should be prepared for uncertainty around repayment. I would not switch simply because the process feels friendlier. I would switch only if the structure matches the kind of flexibility and responsibility I can handle.
My recommendation
Having used the app, I can vouch for its real-world benefits. For borrowers, it's a lifesaver when you're in a pinch and need a quick financial fix without dealing with the bureaucracy of traditional lending institutions. As for lenders, it's a fantastic way to put your money to work and earn some returns while helping others in need.
Moreover, the flexibility of the repayment terms is a major plus. Borrowers can negotiate terms that are manageable for them, and lenders have the freedom to pick and choose requests based on their comfort level. It's a win-win situation for all parties involved.
Final Thoughts
In conclusion, SoLo Funds: Lend & Borrow is a revolutionary app that's democratizing the lending landscape. Whether you're a borrower or a lender, this app provides a platform that's both empowering and rewarding. The sense of community, coupled with the app's transparency and ease of use, makes it a standout choice for anyone looking to engage in peer-to-peer lending.
So, if you're in the market for a lending app that puts people first, give SoLo Funds a whirl. Trust me, it's an experience worth having, and you might just find it to be the financial companion you've been looking for.
SoLo Funds: Lend & Borrow Frequently Asked Questions
Is SoLo Funds available for both Android and iOS?
SoLo Funds is a finance app, and its listed minimum operating system is Android 8.0. Before downloading, check that your phone meets this requirement and that the app is available for your device in your app store. It is free to download, but installing it does not mean you have agreed to borrow money or funded a loan.
Who develops SoLo Funds, and is it free to download?
SoLo Funds is developed by Solo Funds and is free to download. The app is designed for people interested in borrowing or lending through its platform, so its main purpose is different from a general budgeting tool or banking app. Before installing, consider whether peer-to-peer borrowing or lending is the kind of financial service you want to explore.
Can I use SoLo Funds on my phone, and what does it cost to download?
SoLo Funds is a finance app available for Android, and it is free to download. Its listed minimum operating system is Android 8.0, so it’s worth checking your device’s software before installing. The app is designed for people interested in borrowing or lending through its platform, but downloading it does not itself mean you have agreed to a loan or funded one.
What is SoLo Funds and how does it work?
SoLo Funds is a peer-to-peer lending platform that allows users to lend and borrow money directly from each other without the need for a traditional financial institution. Borrowers can request small loans with specific repayment terms, while lenders can fund these requests for a potential return. The app facilitates the entire process securely through its digital platform, ensuring transparency and fairness. Users can connect their bank accounts to manage transactions seamlessly.
Is SoLo Funds safe to use for lending and borrowing?
Yes, SoLo Funds implements various security measures to protect its users, including encryption for data protection and secure bank account linking. The app requires users to verify their identity and provides a community-driven rating system to help users assess the reliability of potential borrowers and lenders. Additionally, the platform offers support and mediation services to resolve disputes, ensuring a safe environment for financial transactions.
Pros
- User-friendly interface for quick navigation.
- Fast approval process for borrowing funds.
- Flexible lending options for users.
- No hidden fees or charges involved.
- Secure transactions with robust encryption.
Cons
- Limited to US residents only.
- Requires a stable internet connection.
- High interest rates for some borrowers.
- Limited customer support availability.
- No option for joint accounts.