Upgrade - Boost Money
- 50.00
- 4.1
- Installs
- 50.00K
- Price
- Free
Screenshots
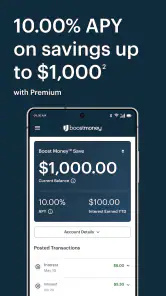
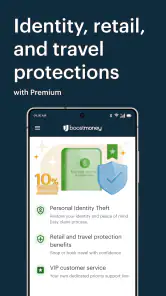
Analysis by Reviewed
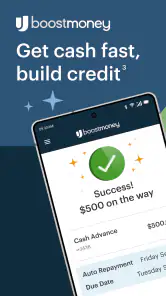
I approached Upgrade - Boost Money as a finance app for people who want to bring everyday spending, saving, and credit-building into one place. Its short store message, “Upgrade,” is brief, but the app’s purpose is clearer when you look at the way those three money goals fit together. Rather than presenting itself as a budgeting spreadsheet or a traditional bank replacement, it is aimed at users who want a more connected view of how daily financial habits can support longer-term progress.
The app is developed by Upgrade, Inc., and it is available free of charge. That matters when deciding whether it is worth trying: there is no purchase price to weigh against the first experience. At the same time, “free” should not automatically be read as “best value for everyone.” A finance app earns its place on my phone only if it helps me make better decisions, reduces unnecessary effort, or gives me a useful path that ordinary banking tools do not provide.
How Upgrade - Boost Money fits into everyday finances
In my experience, the most interesting part of this app is its combined focus. Many financial tools concentrate on one job: a bank app shows balances and transactions, a budgeting app organizes spending, and a credit-focused service centers on credit progress. Upgrade - Boost Money brings the conversation back to the relationship between spending, saving, and credit. That makes it more relevant to someone trying to improve their overall financial routine than to a user who only wants to check a balance.
The app is listed in the Finance category and is rated for Everyone, so its intended audience is broad. That does not mean every financial situation is equally suitable. A person who is already comfortable managing several accounts may find the combined approach less important, while someone building their first consistent money routine may appreciate having fewer separate places to check.
I would describe the app as a companion for financial organization rather than a magic solution. It cannot turn irregular income into a predictable budget or remove the consequences of overspending. Its potential value comes from helping users connect actions that are often treated separately. For example, a person may notice that a spending pattern leaves too little available for saving, while another user may use the app as part of a deliberate effort to handle credit more carefully.
What the free price means in practical terms
Upgrade - Boost Money is free to download and use in the sense that the listed price is free. That makes the initial decision straightforward: you can explore whether the app fits your routine without paying an upfront purchase cost. For someone comparing it with a paid personal-finance tool, that removes one obvious barrier and shifts the question toward usefulness, convenience, and trust.
Still, I would not treat the free price as a promise that every possible financial service connected with the broader Upgrade experience has identical terms. Finance products can involve conditions that depend on the specific service, account, or user situation. My practical advice is to read the details presented inside the app before relying on any feature that affects real money or credit decisions. Free access is a reason to investigate, not a reason to skip careful reading.
This distinction is especially important for users who expect a single app to replace their bank, budgeting system, and credit adviser. A free finance app can deliver genuine value through organization and visibility, but it should still be judged by how clearly it explains actions and consequences. I prefer using it as one informed part of my financial setup rather than assuming that the app alone can manage every decision.
The first useful workflow: turning a money check into a routine
A realistic use case is a weekly money check on the same day each week. I would open the app, review recent spending, look at the amount being set aside, and then ask whether the next few days are likely to put pressure on the plan. The important insight is not simply seeing separate figures; it is comparing them as one routine. If saving repeatedly disappears after discretionary spending, the problem becomes easier to identify than it would be from a quick balance check.
This workflow is more helpful when it stays short. I would avoid opening the app every time I buy something, because that can turn financial awareness into an exhausting chore. A scheduled review gives the app a defined role: it becomes a checkpoint for decisions rather than a source of constant anxiety. Users with variable income can also use the review to separate money already available from money they are expecting later, instead of planning around optimistic assumptions.
That is one of the less obvious ways to get value from a combined finance app. The benefit is not necessarily a special feature; it is the habit of reviewing spending, saving, and credit-related goals together. The trade-off is that the user still has to interpret what they see and act on it. No dashboard can replace a realistic plan.
Where the credit angle can help—and where it cannot
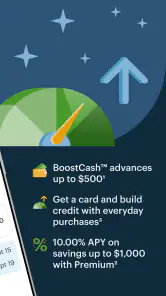
The credit-building focus may appeal to people who are new to managing credit or who want to be more intentional about their financial behavior. In that situation, the app can serve as a reminder that credit is connected to broader money habits rather than being an isolated score to check occasionally. I find that framing more useful than treating credit as a number that should be chased without understanding the surrounding obligations.
However, I would be careful about expecting immediate or universal improvement. Credit outcomes depend on personal circumstances and responsible behavior over time. An app can support awareness, but it cannot make a user’s payments affordable or remove the need to understand terms. Anyone who is already struggling with debt should use the app as an organizational aid, not as a substitute for independent financial guidance or a realistic repayment plan.
A practical approach is to use the credit-related part of the experience to reinforce two questions before taking action: can I comfortably meet the obligation, and do I understand how this decision fits my wider budget? That simple pause is more valuable than pursuing a credit goal in isolation. It also protects users from confusing activity inside a finance app with guaranteed financial progress.
What I would compare with ordinary alternatives
The usual alternative is the banking app already installed on a phone. For basic balances, transfers, and transaction history, a bank’s own app may be more direct. If all I need is to confirm whether a payment went through, opening another finance app may add an unnecessary step. Upgrade - Boost Money becomes more compelling when I want to think about spending and saving alongside credit rather than only viewing a current account.
A spreadsheet is another alternative, especially for users who want total control over categories and formulas. A spreadsheet can be more flexible and easier to customize, but it requires manual discipline and does not necessarily create a convenient financial routine. Upgrade - Boost Money is the more approachable option for someone who does not want to build a personal system from scratch. The spreadsheet remains better for detailed household planning, shared budgets, or unusual income patterns that need custom calculations.
Dedicated budgeting apps may offer deeper category analysis or more granular planning. I would choose one of those when my main goal is tracking every category, setting detailed limits, or studying spending trends. I would choose Upgrade - Boost Money when the priority is a simpler connection between daily money management and credit awareness. The choice depends less on which app sounds more complete and more on whether the user wants depth in one area or a broader financial routine.
Three ways to use it more thoughtfully
- Use a fixed review rhythm. A weekly check is often more sustainable than repeatedly refreshing balances. Look for patterns and decisions, not just movement in the account.
- Separate visibility from commitment. Seeing a credit-related option does not mean it is appropriate for your budget. Treat every financial action as a separate decision that deserves its own review.
- Pair the app with one outside safeguard. Keep a simple emergency buffer, calendar reminder, or written spending limit so that the app supports your system instead of becoming the entire system.
The third point is particularly important for people with irregular pay or several financial obligations. A combined app can make the overall picture easier to understand, but it may not reflect every personal commitment in the way a carefully maintained budget does. I would use it to improve awareness while keeping a separate note for bills, annual expenses, and financial priorities that need special attention.
Performance expectations and the decision to install
The current version is 1.3.0 and requires iOS or Android 12 or later. That requirement is reasonable for users with a relatively recent phone, but it immediately excludes people using older devices. Before planning to move an entire financial routine into the app, I would check the operating-system version on the phone that will be used most often. A finance tool is not useful if it cannot be accessed when needed.
The app has passed the early discovery stage with more than fifty thousand installs. Its average rating is 4.1 from over one hundred ratings, which suggests a generally positive reception while still leaving room for mixed experiences. I would read that rating as a reason to try the app personally, not as proof that it will suit every financial workflow. Finance apps are especially sensitive to differences in expectations: a user seeking a simple overview may be satisfied, while another expecting advanced budgeting controls may judge it more strictly.
The Everyone content rating makes the app approachable for a wide audience, but responsible use still depends on age, financial knowledge, and personal circumstances. Younger or inexperienced users should take extra care with any feature involving credit or financial commitments. The accessible presentation should not be mistaken for a guarantee that every decision is low risk.
Where the experience may feel limited
My main reservation is that a broad “spend, save, and build credit” approach can create high expectations. Users may assume that one app will provide the detailed controls of a specialist budgeting tool, the account services of a bank, and the educational depth of a credit adviser. If the goal is highly customized household budgeting, complex cash-flow forecasting, or extensive reporting, I would probably look for a more specialized companion.
There is also a mental trade-off in combining several goals. A user may become focused on improving credit while overlooking whether spending remains affordable, or may prioritize saving in a way that leaves essential bills exposed. The app’s combined perspective is valuable only when the user keeps priorities in the right order. Essential expenses and financial stability should come before chasing an attractive secondary goal.
Another possible friction is the need to verify details before acting. That is not a flaw unique to this app; it is a basic requirement for any finance product. I would not make a significant decision from a headline, notification, or simplified summary alone. I would open the relevant explanation, check the conditions, and consider how the action affects my complete budget. People who want effortless, automatic answers may find that level of responsibility inconvenient.
Who will get the most value
I think the app is best suited to someone who wants a gentle structure for improving financial awareness. It may be a good fit for a user who currently checks a bank balance without connecting it to saving goals, or for someone who wants to think about credit as part of a larger money plan. The free price also makes it a low-risk starting point for testing whether this combined approach feels natural.
It is less suitable for a person who already has a detailed budgeting system and only needs fast banking functions. In that case, the extra layer may not justify another app. I would also hesitate to recommend relying on it alone for a household with complicated finances, shared expenses, multiple income sources, or significant debt. A more specialized budget, professional advice, or both may be better for those situations.
For a student or first-time credit user, the app could be useful as a prompt to develop better habits, provided the user understands that credit-building is gradual and personal. For a busy worker, its value may come from consolidating a short weekly review. For someone who dislikes financial apps entirely, the free price may encourage a trial, but the app will only help if the person is willing to act on what it shows.
My final recommendation
Upgrade - Boost Money is worth trying when you want one free finance app to connect spending awareness, saving intentions, and credit-focused habits. I like its broader perspective more than I would like a tool that only displays transactions, and the absence of an upfront price makes experimentation easy. Its strongest value is behavioral: it can encourage a regular review and help users see how everyday choices relate to longer-term goals.
I would skip it if I need a highly detailed budgeting laboratory, a complete replacement for my bank, or a guaranteed shortcut to better credit. In those cases, a specialist alternative may be more appropriate. I would also avoid making any financial commitment simply because the app presents it conveniently. The right use is measured and deliberate: review the information, compare it with your own budget, and act only when the decision makes sense.
Overall, I see Upgrade - Boost Money as a practical free starting point rather than an all-purpose financial command center. Its 4.1 average rating and growing install base make it credible enough to explore, while its limitations are a reminder to keep expectations realistic. If your main need is a clearer connection between spending, saving, and credit habits, I would give it a try. If your finances require deep customization or professional-level guidance, I would keep looking for a more focused tool.
Pros
- Simple interface makes balance and upgrade options easy to understand.
- Progression feels rewarding as upgrades gradually increase earning potential.
- Short play sessions suit users looking for quick
- casual entertainment.
- Clear visual feedback helps show the effect of each purchased upgrade.
- Works well for idle-style players who enjoy steady
- incremental progress.
Cons
- Progress can become repetitive once the main upgrade loop is familiar.
- Some features may feel limited without watching ads or making purchases.
- The focus on virtual money may not appeal to players seeking deeper gameplay.
- Frequent reward prompts can interrupt the otherwise simple experience.
- Performance and battery use may vary on older Android or iOS devices.
- Category
- Finance
- Version
- 1.3.0











