Borrow Money Instantly - Fundi
- 2.13K
- 4.7
- Installs
- 500.00K
- Price
- Free
Screenshots
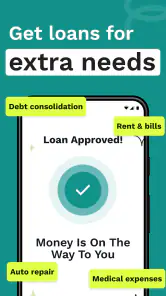
Analysis by Reviewed
When an unexpected bill lands between paydays, the appeal of Borrow Money Instantly - Fundi is easy to understand. It is a free finance app from Sunny Pal Singh Gill, presented as a way to request an instant loan and seek fast approval for a cash advance. I approached it as a practical borrowing tool rather than a general money-management app, and that distinction matters: Fundi is aimed at a short-term need, not at helping me build a complete budget or long-term savings plan.
My first impression is that the app’s promise is deliberately direct. The store summary focuses on borrowing money today, while the short description simply identifies it as “Fundi.” That makes the intended use clear, but it also means I would not install it casually just to explore finance features. A loan application deserves more attention than a normal utility download because the important decision is not only whether the application is easy to use, but also whether the repayment terms suit my situation.
How Fundi feels in its current state
Fundi belongs to the instant-loan side of the finance category. The current version is 1.0.6, and the app has reached over 500 thousand installs with an average rating of 4.7 from around 38 thousand ratings. Those figures suggest that many people have been willing to try it, but popularity should not be confused with affordability. A borrowing app can be convenient and still be the wrong choice if the total repayment is difficult to manage.
The app is free to install, and its content rating is Everyone, which makes the basic download approachable for a broad audience. In practice, however, the age label does not make borrowing appropriate for every person. I would treat the rating as an indication of app accessibility, not as financial advice. Anyone considering an application should be old enough and legally eligible to borrow in their location, and should read every repayment detail shown before accepting anything.
The strongest part of Fundi’s positioning is speed. If I have a time-sensitive expense, a simple route from opening the app to requesting a cash advance can be more useful than a traditional lender’s slower process. That convenience is valuable when the need is genuinely temporary and I already know exactly how the repayment will fit into my next income cycle.
At the same time, “instant” should be understood as the product’s intended experience, not as a guarantee that every request will be approved or funded in the same way. Approval depends on the application process and the information requested from the borrower. I would avoid planning a critical payment around money that has not yet been approved and made available.
The practical workflow I would use
I would begin by opening Fundi only when I had a defined amount and a defined reason for borrowing. Instead of entering a vague figure because the app makes access feel easy, I would calculate the exact shortfall. That small habit reduces the chance of borrowing more than necessary and makes it easier to compare the final repayment with my available income.
Before submitting anything, I would read the full offer carefully, focusing on the total amount to repay, the due date, any applicable charges, and what happens if repayment is late. The most important number is not the amount deposited into my account; it is the complete amount leaving my account later. If the app displays several repayment choices, I would compare them side by side rather than choosing the fastest-looking option.
I would also keep a record of the application and repayment information outside the app. A note containing the borrowed amount, the total repayment, and the due date is a useful safeguard. It prevents the common mistake of remembering only the cash received while forgetting the actual obligation. This is one of the less obvious ways to use a fast-loan app responsibly: treat the transaction as a scheduled financial commitment from the beginning.
For example, imagine that a necessary household payment arrives a few days before payday. Fundi may be worth considering if I know the upcoming income is reliable, the repayment amount is clearly affordable, and the cost of using the service is lower than the consequence of missing that payment. I would not use it for a spontaneous purchase, a recurring shortfall, or another loan repayment. In those situations, the app may hide the underlying problem rather than solve it.
What the current release means for existing users
The May 22, 2023 release date places Fundi among relatively recent finance apps rather than a long-established banking product. Its current 1.0.6 version shows that the app has moved beyond its first release, but a version number alone does not tell me which parts changed or how substantial those changes were. I would therefore judge the present experience by the clarity of the live application flow and the terms shown at the moment of borrowing, not by assuming that an update automatically makes the service better.
For someone already using Fundi, the most practical benefit of staying current is access to the version the developer currently distributes. Updating before starting a new application is sensible because an older build may not match the current screens or process. I would still review the offer from the beginning after an update instead of relying on what I remember from a previous loan. Financial terms and eligibility decisions should be checked each time.
The developer, Sunny Pal Singh Gill, has brought the app to a substantial audience, reflected in its install count and strong average rating. That gives Fundi a meaningful level of visibility, but it does not replace my own checks. Ratings often reflect ease of use or a successful individual experience; they do not tell me whether a particular offer is suitable for my income, location, or emergency.
Existing users should also pay attention to changes in the application journey. A small interface adjustment can alter where important information appears, especially around repayment dates or the final confirmation step. My preferred habit is to slow down at the last screen, read the amount again, and save confirmation details. A fast approval process is useful only when I remain in control of what I am agreeing to.
Where Fundi is more useful than usual alternatives
Compared with asking friends or family, Fundi offers a more structured digital route and avoids the personal discomfort that can come with explaining an emergency. Compared with a conventional bank loan, its instant-loan focus may feel more appropriate for a smaller, urgent gap rather than a major planned purchase. That is the narrow situation in which I see its strongest value: a temporary need, a clear repayment source, and a process that does not require me to manage a long borrowing plan.
It is also more targeted than a standard budgeting app. A budgeting tool can show me where my money is going, but it cannot address an immediate cash shortage by itself. Fundi is designed around the borrowing request, so it may be more relevant when the immediate question is how to bridge a short gap rather than how to categorize spending.
However, a credit union, established bank, employer advance, or a negotiated payment extension may be better alternatives in other circumstances. Those options can be preferable when I need a larger amount, more time to repay, lower overall cost, or personal guidance. If I am repeatedly short before payday, I would choose a budgeting review or debt-support conversation instead of taking another instant loan. The convenience of Fundi should not become a substitute for fixing recurring cash-flow pressure.
Important friction before requesting money
The main limitation is inherent in the category: speed can encourage rushed decisions. A clean mobile flow may make borrowing feel like a normal purchase, but the consequences last longer than a purchase confirmation. I would be especially cautious if the app presents a repayment date that arrives before my next dependable income, or if the total repayment is difficult to understand at a glance.
Another point of friction is that a loan request requires personal and financial information. I would read the app’s permission prompts and privacy explanations carefully, install it only from the official Android or iOS store, and avoid entering sensitive details through messages or unofficial pages. I would never send identity or banking information to someone claiming to represent the service outside the normal application process.
Fundi is not the right choice for someone who needs certainty that money will arrive immediately. The store positioning emphasizes fast approval, but an application still involves a decision. It is also not a good fit for someone who cannot identify the exact repayment source. In that case, the problem is not merely a temporary timing mismatch, and another loan could leave the borrower in a worse position.
I would skip it as well if I were comparing offers only by the amount available. The better comparison is the total cost, repayment schedule, and flexibility of each option. A smaller advance with a manageable repayment may be safer than a larger one that creates pressure. If the final terms are unclear, I would stop rather than continue simply because I had already entered information.
Small habits that make the app safer to use
My first useful habit would be to calculate affordability before opening the request screen. I would subtract essential expenses, existing repayments, and a modest emergency buffer from my expected income. Only the remaining amount should influence whether a new repayment is realistic. This prevents the app’s available amount from becoming the deciding factor.
Second, I would use Fundi for a single, clearly documented purpose and keep the repayment date visible in my personal calendar. A calendar reminder is particularly useful because a fast loan can be completed in minutes while the obligation may be easy to overlook later. I would set the reminder early enough to move money or contact the provider if a problem appears.
Third, I would compare the offer with a non-borrowing solution before accepting it. A bill provider may allow a payment arrangement, an employer may offer an advance, or a trusted person may provide a no-cost alternative. These possibilities are not always available, but checking them takes little time and can reveal that borrowing is unnecessary.
Finally, I would never use one advance to cover another. That pattern turns a short-term bridge into a cycle. Fundi can be useful when the timing of income and expenditure is temporarily misaligned; it is much less suitable when the income itself is not enough to cover normal living costs.
What I would watch as the product develops
Because Fundi is at version 1.0.6, I would watch future updates for clearer explanations around eligibility, repayment, and the complete cost of borrowing. Those are the areas that matter most to users, more than cosmetic changes. A useful evolution would make the final obligation impossible to miss and keep the path from request to confirmation easy to understand.
I would also look for consistency between the information shown before an application and the information shown at the final decision. For a finance app, trust comes from predictable explanations. If the interface changes, existing users should still be able to locate their repayment details and records without confusion.
The strong rating and broad install base make Fundi worth considering for a narrow, urgent use case, but they do not remove the need for personal judgment. I would recommend it to a financially stable user who needs a temporary cash advance, understands the full repayment, and has a dependable plan for paying it back. I would point someone with ongoing debt, uncertain income, or a need for long-term credit toward a bank, credit union, payment arrangement, or debt adviser instead.
My overall view is cautiously positive. Fundi is most convincing when it is treated as a short bridge, not as extra income. Its free installation, focused purpose, and fast-approval approach make it easy to consider in an emergency, while the same simplicity creates a risk of acting too quickly. If I used Borrow Money Instantly - Fundi, I would decide the amount before opening it, read the complete repayment terms twice, save the due date, and accept only what my confirmed income can comfortably cover.
Pros
- Fast application process with minimal paperwork required
- Clear repayment schedule helps users plan their finances
- Useful for handling unexpected short-term expenses
- Loan details are presented before accepting an offer
- Application can be completed from a mobile device
Cons
- Interest and service fees may make borrowing expensive
- Approval and loan terms can vary by applicant
- Late payments may lead to additional charges
- Short repayment periods can strain limited budgets
- Availability may depend on location and eligibility
- Category
- Finance
- Version
- 1.0.6











