Borrow Money: Fast Cash Loan
- 1.06K
- 4.7
- Installs
- 100.00K
- Price
- Free
Screenshots
Analysis by Reviewed
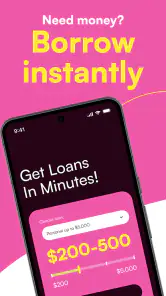
Borrowing money through a phone can feel intimidating, especially when you are already dealing with an unexpected bill. I approached Borrow Money: Fast Cash Loan with that in mind. It is a finance app from Dollar Loan Center built around the idea of requesting a cash advance through a mobile process rather than starting with a branch visit or a long search through traditional banking options. My first impression is that it is aimed at urgency and simplicity, but it still deserves careful use because a quick loan is a financial commitment, not just another app download.
The app is free to install and is rated for Everyone, which makes the basic download accessible to a wide audience. It has reached over 100 thousand installs and holds a 4.7 average from around 21 thousand ratings, with roughly 1.1 thousand written reviews. Those figures suggest that many people have found the experience useful, although they should not be mistaken for a promise that every applicant will receive money or the same terms.
I would describe it as a practical starting point for someone who needs to explore a short-term borrowing option quickly. I would not treat it as a replacement for budgeting, savings, or a regular bank account. The most important question is not simply whether the app is easy to open, but whether repaying the advance will fit comfortably into your next pay cycle.
What to expect before requesting money
The store summary presents the app as a way to get a cash advance, including for people concerned about bad credit. That positioning is useful for setting expectations: this is not a general personal-finance dashboard, investing tool, or credit-building course. Its purpose is much narrower. You open it because you want to explore borrowing money, not because you want to track spending or compare every loan product on the market.
That narrow focus is one of its strengths. A first-time user does not have to sort through unrelated budgeting features before reaching the main reason for installing it. At the same time, the narrow focus means I would not choose it as my only finance app. If your real problem is recurring overspending, a budget planner may help more. If you need a large, long-term loan, a bank or credit union is usually a more suitable place to compare repayment structures.
The developer, Dollar Loan Center, is visible as part of the product identity rather than the app feeling like an anonymous calculator. That matters when you are entering personal and financial information. Even so, I recommend reading every screen carefully. A fast application flow can make it tempting to tap through automatically, and that is exactly when a borrower may miss an important condition.
The app can make the request process more convenient, but convenience should never replace checking the total repayment amount. Before accepting anything, I would look for the amount received, the amount due, the repayment timing, and any applicable charges shown during the process. Those details matter more than the speed of the interface or the app’s rating.
Who will get the most value from it
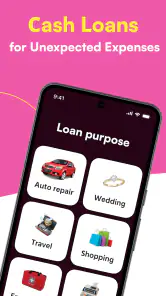
This app makes the most sense for an adult who has a specific, short-term cash gap and wants to investigate a digital borrowing route from Dollar Loan Center. A realistic example would be a necessary car repair appearing a few days before payday. In that situation, I would use the app to see whether an advance is available, compare the repayment obligation with my incoming pay, and decide only after confirming that the next budget can absorb it.
It may also suit someone who feels uncomfortable beginning with a phone call or office visit. Completing an initial request from a smartphone can give that person a more private and organized way to review the process. The app is available at no purchase price, so installing it to examine the available path does not itself require a payment.
I would be more cautious if you are considering borrowing for a nonessential purchase, trying to cover several old loans, or repeatedly using advances to reach the next paycheck. In those situations, the app may solve today’s shortage while leaving the underlying problem untouched. Someone who needs time to compare annual costs, repayment periods, and larger loan amounts may be better served by a bank, credit union, or a reputable comparison service.
Starting with the installation and account setup
The current release is version 0.2.2 and supports Android 7.0 or newer. That makes it usable on many older Android phones, which is helpful for people who do not have a recent device. After installing, I would keep the process calm and deliberate: use a secure connection, make sure the app is the genuine Dollar Loan Center product, and have the information you normally need for a financial application available before beginning.
A first-time borrower should expect the app to focus on eligibility and application details rather than entertainment or customization. I would not rush through fields simply because the interface is on a phone. Check names, contact information, income details, and requested amounts before moving forward. A typo in a financial application can create avoidable delays or confusion, and correcting it later is usually less convenient than entering it carefully the first time.
One useful habit is to decide your maximum comfortable repayment before opening the request screen. Do not start with the largest amount the app appears to allow. Start with the smallest amount that would genuinely solve the immediate problem, then compare the complete repayment obligation with your budget. This approach reduces the risk of turning a manageable repair or bill into a larger commitment.
I would also prepare to verify that the phone number and email address connected with the application are ones you actively monitor. A borrower can miss an important update when using an old address or a number that is no longer in service. This is a small setup detail, but it becomes important when the process depends on timely communication.
Reaching the first meaningful result
The first meaningful success is not necessarily receiving money. For a careful user, it is reaching a clear decision: either the available option fits the budget, or it does not. I would open the borrowing flow, enter accurate information, and stop to review the result instead of treating approval as the finish line.
If the app presents an offer, read the figures as a complete package. Compare what would arrive in your account with what you would need to repay. Then ask yourself whether that repayment would still be comfortable after rent, food, transportation, utilities, and existing obligations. A loan that technically fits on paper may still be stressful if your next paycheck is already committed.
If the request does not move forward, avoid repeatedly changing information just to force a different result. Accurate details are more important than trying to make the application look more favorable. I would save any relevant confirmation shown in the process and contact the developer’s official support route if the app instructs me to do so, rather than relying on unofficial messages or third-party claims.
For the car-repair example, my workflow would be straightforward. I would first confirm the mechanic’s actual bill, request only the amount needed, inspect the repayment details, and then compare that obligation with my next two weeks of expenses. If the numbers leave no room for groceries or transportation, I would treat that as a warning and look for another solution instead of accepting automatically.
Confusing points that deserve extra attention
The phrase “fast cash” can create the impression that funds are guaranteed or immediate for everyone. I would not read it that way. It describes the app’s intended convenience, not a personal promise. Eligibility, timing, and available terms can depend on the application and the information supplied. The safest mindset is to use the app to explore an option, not to promise a landlord, repair shop, or family member that money will arrive before you have confirmed the outcome.
Another common confusion is treating a high average rating as evidence that the financial terms will be favorable for every person. Ratings mainly tell me that many users liked their experience with the app. They do not replace reading the individual offer. A smooth interface and a suitable loan are separate questions, and I would judge them separately.
It is also easy to confuse the app’s free installation with free borrowing. The download costs nothing, but borrowing money can involve repayment obligations. I would never accept an advance based only on the fact that the app itself is free. The important cost is the full amount connected with the borrowing request, shown during the application process.
People with bad credit may be especially interested because the store description speaks directly to that concern. I appreciate that the app does not present traditional credit history as the only issue worth considering. Still, bad credit does not mean a borrower can ignore affordability. If an advance carries a repayment amount that your budget cannot handle, approval would not make it a good decision.
Finally, do not assume that every problem is an app problem. A slow response may relate to application review, account details, connectivity, or the specific borrowing request. I would first check the entered information and connection, then follow the in-app guidance. I would avoid sending sensitive information to anyone who contacts me through an unverified social account or message.
How it compares with familiar alternatives
Compared with visiting a traditional lender, this app offers a more phone-centered starting point. That can save time and make the first step less awkward for someone who wants to review an option privately. The trade-off is that a mobile screen can make important financial details feel smaller or easier to skim. In a branch or scheduled conversation, a person may be more likely to ask questions before proceeding.
Compared with a bank or credit union, the app is more focused on short-term access and may appeal to people who are worried about their credit profile. A bank may be better for an established customer who qualifies for a lower-cost product, needs a longer repayment period, or wants broader financial guidance. I would compare the total cost and timing rather than assuming one channel is automatically better.
Compared with borrowing from family or using an emergency fund, an app-based advance can feel more private and structured. However, those alternatives may avoid some borrowing costs when they are genuinely available and handled responsibly. An emergency fund is usually the healthier first choice because it does not create a new repayment date. The app becomes more relevant when those options are unavailable and the need is legitimate.
Compared with a credit card, the right choice depends on the existing account terms and repayment discipline. A credit card may offer flexibility, but carrying a balance can also become expensive. The useful comparison is not “app versus card” in the abstract; it is the exact amount repaid, the due date, and the consequences of missing it. I would write those details down before choosing.
Small habits that make the experience safer
My first tip is to use the app for one clearly defined need rather than requesting extra money “just in case.” A smaller request is easier to evaluate and repay. My second is to take a screenshot or personal note of the final terms shown to you, provided that doing so does not expose sensitive information to anyone else using your phone. This gives you a reference when planning the repayment.
A third useful habit is to open your normal budget before accepting anything. List fixed bills first, then food, transportation, and existing debt payments. Only after those essentials are covered should you decide whether the new obligation fits. This simple order prevents the common mistake of treating the advance as available spending money instead of money that already has a job.
I would also avoid applying while distracted, rushed, or under pressure from another person. Financial applications require accurate answers, and pressure can lead to accepting a larger amount or overlooking a condition. If the need is urgent, slowing down for a few minutes is still worthwhile.
Keep the app updated through the normal Android store process, especially because the current version is still an early-looking 0.2.2 release. An update may improve the experience, but I would still review each screen after an update rather than assuming the flow is identical. The minimum Android requirement of 7.0 is friendly to older devices, yet an older phone should still have enough storage and a stable connection for a financial task.
When I would choose another path
I would skip this app if I needed a detailed long-term repayment plan, debt consolidation advice, investment tools, or everyday account management. Its identity is centered on borrowing money, so using it for unrelated financial goals would be a mismatch. I would also look elsewhere if I had enough savings to cover the expense without creating a new obligation.
I would pause if the repayment date conflicts with another essential bill. Even a successful advance can become harmful when several deductions or payments land together. In that case, speaking directly with the bill provider, asking about a payment arrangement, or seeking help from a trusted nonprofit may be more appropriate than adding another short-term loan.
I would also avoid relying on the app as a repeating payday routine. If the same shortfall appears every month, the better next step is to examine income, fixed expenses, and existing debt. The app may be useful for a one-off emergency, but repeated borrowing is a sign that a broader solution deserves attention.
My next-step recommendation for a first-time user
If you decide to try it, begin with a specific amount and a specific reason. Install the free app, confirm that you are using the Dollar Loan Center product, and complete the initial information carefully. When a result appears, treat it as something to evaluate rather than something you must accept. The first successful action should be understanding the obligation clearly.
For me, the app’s strongest point is the focused mobile route for people who want to investigate a cash advance without starting with a traditional lender visit. Its main weakness is not necessarily the interface; it is the risk that speed can encourage a rushed financial decision. That risk belongs to the category as a whole, but it is especially important here because the app’s appeal is convenience.
Borrow Money: Fast Cash Loan is worth considering when a genuine short-term need requires a quick digital starting point and the repayment plan fits your budget. It is not the right answer for every financial problem, and its 4.7 average should not replace personal due diligence. I would recommend approaching it with a written budget, a modest request, and a firm willingness to walk away if the numbers do not work.
Released on August 6, 2024, the app is free, available for Everyone, and developed by Dollar Loan Center. Those details make it easy to try, but the decision to borrow should remain separate from the decision to install. If the app helps you reach a clear, affordable solution for a real emergency, it can be useful. If it only postpones a recurring money problem, a different financial strategy will serve you better.
Pros
- Quick application process with minimal paperwork required.
- Clear repayment schedules help users plan their finances.
- Available from a smartphone without visiting a physical branch.
- May help cover urgent
- unexpected expenses.
- Loan status and payment details are easy to check in the app.
Cons
- Interest rates and fees may be high compared with traditional bank loans.
- Approval and loan amounts can vary based on eligibility checks.
- Late payments may lead to extra charges or affect your credit profile.
- Not available in every country or for all types of borrowers.
- Sharing financial and personal data raises privacy considerations.
- Category
- Finance
- Version
- 0.2.2











